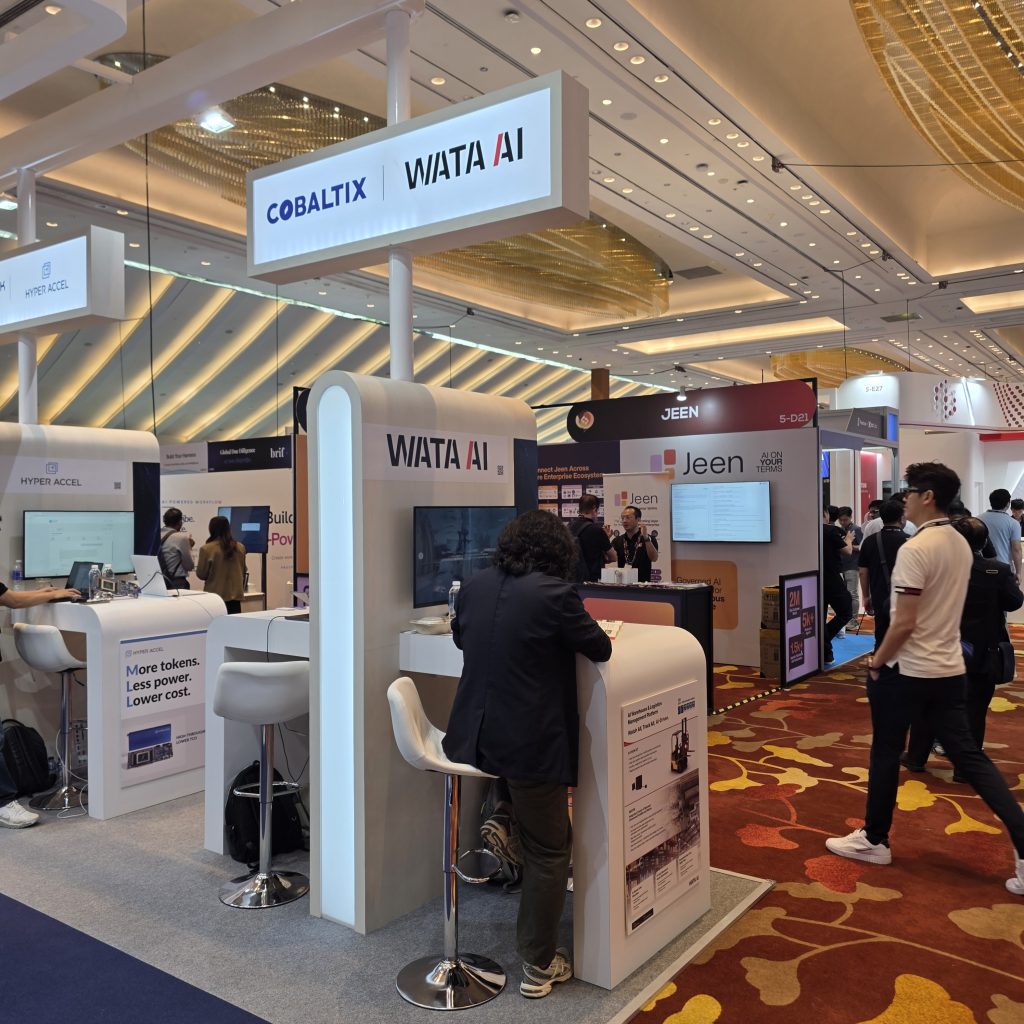
At TechWeekSingapore2026, I have been looking at technologies from the perspective of freight forwarding and logistics: What operational problem does this actually solve?
The core value proposition appears to sit alongside the WMS rather than replacing traditional WMS functionality.
There are two distinct applications.
1. Physical handling accuracy
WATA addresses the physical execution layer of warehouse operations:
• Putaway accuracy: verifying that the correct pallet is placed in the correct pallet location. • Inventory accuracy: checking what pallet is physically located at each pallet position. • Outbound accuracy: verifying that the correct pallet is retrieved and despatched.
Pallets do not necessarily require a barcode, although identification would improve the process.
The current application therefore appears best suited to homogeneous products with known and defined pallet configurations.
This distinction is important: a WMS knows where a pallet should be. WATA is trying to establish whether the physical pallet is actually there.
2. Digital twin and warehouse optimisation
The warehouse can be modelled digitally to analyse:
• current productivity and material flows; • as-is versus to-be scenarios; • alternative warehouse and racking configurations, including adjustable pallet racking systems; • the productivity impact of layout changes before physically implementing them.
This takes the application beyond accuracy and control into warehouse engineering and continuous improvement.
Current limitations
Based on the solution demonstrated to me, there are some limitations to consider:
• The current solution appears better suited to single-user warehouse environments. Multi-user operations with different customers, SKUs and handling requirements introduce considerably more complexity. • Inventory, putaway, picking and outbound verification currently operate at full-pallet level. • FIFO, LIFO, batch and expiry-date control become problematic where two pallets containing the same SKU and having the same pallet configuration are physically interchanged. The system cannot independently determine inbound date, batch number or expiry date from the pallet configuration alone.
Overall, it was interesting to see technology addressing the physical accuracy gap between what the WMS records and what is actually happening on the warehouse floor.
It’s good to see solutions being developed specifically around logistics operations, and I hope we see more technology providers addressing the particular challenges of freight forwarding and logistics over time.
At TechWeekSingapore2026, I have been looking at technologies from the perspective of freight forwarding and logistics: What operational problem does this actually solve?
One of the solutions worth looking at is SOTI (soti.net). We spend a lot of time talking about WMS, TMS, automation and AI.
But there is another layer we often overlook: the device the warehouse operator or driver actually holds in their hand.
SOTI manages and secures these mobile and rugged devices across platforms including Android and Windows, and supports manufacturers commonly used in logistics such as Zebra, Honeywell, Datalogic and Panasonic.
Where does this become operationally interesting?
A warehouse handheld can be locked down so the operator only has access to the applications and functions required for the job.
Different configurations can be applied to warehouse staff, drivers and supervisors.
Geofencing takes this further. Device policies can change depending on whether the device is inside an approved warehouse, depot or other location.
Then there is downtime. When a scanner stops working, the problem is not simply an IT problem. It becomes an operational problem. SOTI allows support teams to remotely diagnose devices, collect logs and examine device, application and battery behaviour without necessarily having the device physically in front of them.
Another practical logistics application is controlled photo capture. Images of damaged cargo, loading conditions or proof of delivery can be captured, automatically transferred to a central repository and removed from the device afterwards.
My takeaway
The easiest way to understand where SOTI fits into logistics is perhaps this:
The WMS manages the inventory.
The TMS manages the transport. The handheld connects the employee to those systems. SOTI manages and protects that connection.
As logistics operations become increasingly digital, the devices used on the warehouse floor and in the field are no longer just hardware. They are part of the operational infrastructure.
At TechWeekSingapore2026, I have been looking at technologies from the perspective of freight forwarding and logistics: What operational problem does this actually solve?
MetaCompliance: More Than Cybersecurity Training
At first glance, MetaCompliance appears to be a cybersecurity awareness and compliance platform. Looking at it from a freight forwarding and logistics perspective, however, I see a much broader application.
Our industry depends heavily on people knowing and following the correct procedures.
There are regulatory and operational requirements such as dangerous goods, cargo security, customs, export controls and GDP. There are financial controls covering credit, payments, billing and approvals. Then there are customer-specific SOPs, product training and functional training for operations, sales, customer service, finance and warehousing.
The challenge isn’t simply:
“Have we trained our employees?”
It is:
“Can we demonstrate that the right employee received the right information, understood it and acknowledged the latest version?”
This is where MetaCompliance becomes interesting.
The platform combines learning with policy management, allowing companies to distribute training and policies to relevant employees and track completion and acknowledgement.
One capability I particularly like is Content to Course. Existing company material, such as policies and PDFs, can be converted into structured learning content and assessments.
For a freight forwarder, that could mean turning a customer SOP, revised operational process, compliance requirement or new product procedure into targeted training rather than simply emailing another PDF.
Cybersecurity remains an important part of the solution, particularly in an industry handling large volumes of external emails, documents, shipment information and payment instructions.
But I think the bigger opportunity is human compliance.
A document repository tells employees where the procedure is.
A training and compliance platform helps establish whether the people who need to follow it actually know it.
And in freight forwarding and logistics, where a single missed procedure can result in operational, financial or regulatory consequences, that is highly relevant.
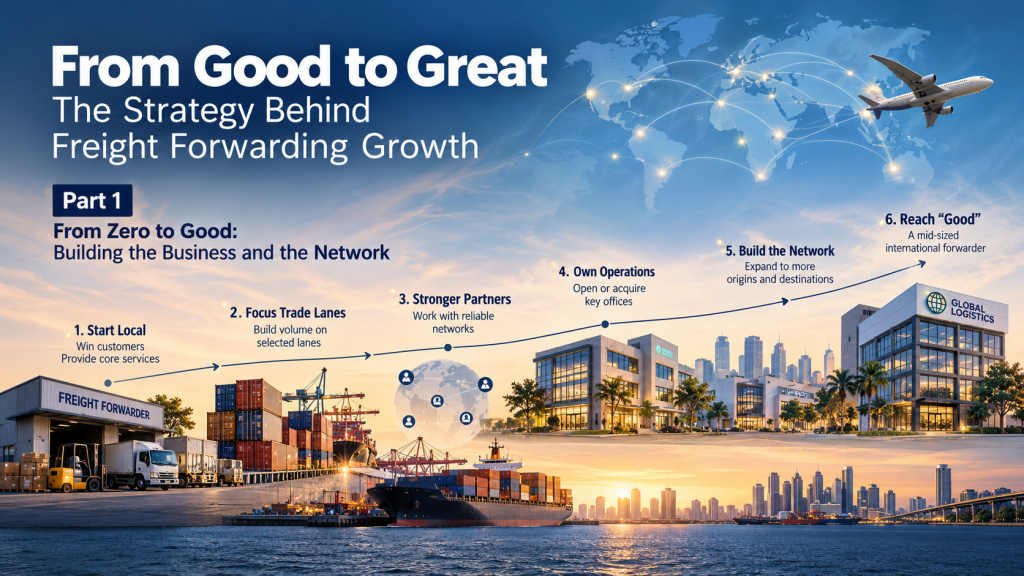
Part 1: From Zero to Good: Building a Freight Forwarding Company
A proven model of building a freight forwarding company:
Start locally. Win customers. Develop relationships with overseas forwarders. Concentrate on trade lanes where the business grows. Replace partners with your own operations when sufficient volume justifies the investment. Then repeat the process.
Over time, a small local forwarder can become a substantial international company.
Two characteristics make this model particularly interesting.
The first is that freight forwarding can be operated as an asset-light business. The company makes little to no investment in capital-intensive logistics assets such as warehouses, CFS facilities, large truck fleets or other physical logistics infrastructure. It may own selected assets, such as office premises, individual trucks or equipment, where there is a practical or economic reason to do so, but physical asset ownership is not central to the business model.
The second is the way growth can be financed.
Instead of relying heavily on debt or external investors, expansion can be financed primarily from the profits generated by the existing business.
Together, these principles create a disciplined growth model:
Build the business first. Let the business justify the investment. Use the investment to strengthen the network. Then allow the stronger network to create more business.
This is the journey from zero to good.
Stage 1: Start as a Local Forwarder
The company begins with the fundamental forwarding services:
It can control the local side of the shipment but cannot independently provide the same service overseas.
So it joins or develops relationships with a network of other independent forwarders that provide equivalent capabilities at origin and destination.
That creates the first viable international product:
Local capability + overseas partner = door-to-door forwarding
Very little fixed network investment is required.
The company does not need its own operation in Germany to offer a Singapore-Germany service. A German forwarding partner can provide the pickup, customs clearance, handling or delivery required at the other end.
The same model can be repeated across multiple countries.
The company’s primary assets at this stage are therefore not warehouses or CFS facilities. They are its people, customer relationships, forwarding expertise, carrier relationships and overseas partner network.
Capital requirements remain relatively modest, allowing management to concentrate its available resources on generating and managing business.
Stage 2: Develop Focused Trade Lanes
As the company grows, certain trade lanes naturally become more important.
Perhaps Singapore-Germany becomes significant, or China-Singapore, or Singapore-US.
This matters because volume becomes concentrated rather than simply increasing in aggregate.
The company develops deeper relationships with selected overseas partners on those lanes. Business begins flowing in both directions:
Locally controlled business → overseas partner
and
Partner-controlled/routed business → local company
This creates a reinforcing cycle:
More local business → stronger overseas relationship → more routed business → more volume → greater relevance to the partner → more routed business
The relationship becomes increasingly valuable to both companies.
This is an important stage in the development of the forwarder because it begins creating trade-lane density.
Instead of trying to become equally strong everywhere, the company develops greater strength on selected origin-destination combinations where its customer base and partner relationships are producing meaningful volume.
At this stage, partner selection becomes strategically important.
Stage 3: Move Toward Stronger Network Partners
As the business becomes larger, the limitations of a loose collection of small independent agents eventually become visible.
Service levels vary. Systems differ. Communication standards differ. Financial strength differs. Management priorities differ.
And when something goes wrong, accountability can become difficult.
This creates a problem for the growing forwarder.
The customer does not particularly care that several independent companies are involved in moving the shipment.
The customer bought a door-to-door service.
One solution is therefore to develop a closer relationship with a larger independent or medium-sized forwarding network.
This may reduce some flexibility in choosing individual agents, but it can improve:
coverage, consistency, reliability, systems, buying power and accountability.
The company is beginning to sell more than transportation between two points.
It is developing a more dependable network product.
Importantly, this remains a capital-efficient way of improving international capability.
Rather than opening dozens of overseas offices, the company uses stronger partnerships to extend its reach while concentrating its own resources on the markets where it already has meaningful business.
Stage 4: Replace Partners With Owned Operations
Eventually, a particular trade lane becomes sufficiently important that using an agent is no longer the optimal solution.
This creates the first major critical-mass decision.
The question becomes:
At what level of existing and expected business does owning the overseas operation produce better economics, control and service than continuing to use an agent?
The company may establish its own office or acquire an existing local forwarder. That changes both the economics and the product. The company gains control over both ends of the shipment.
It can retain more of the forwarding margin, improve accountability, introduce common processes and service standards, and gain direct access to customers in the overseas market.
But something even more important happens.
The new office does not only service the shipments that justified opening it.
It starts generating business itself.
Salespeople in the new country win local customers. Those customers generate exports and imports. Some of that freight moves to existing offices elsewhere in the network.
The growth cycle therefore expands:
Existing volume → own office → improved service and control → local sales → new customers → additional bilateral volume → stronger trade lane
The investment begins reinforcing the business that originally justified it.
Stage 5: Build an Owned Network
The same logic can now be repeated. A second market reaches critical mass. Then another. Some locations are opened organically. Others may be acquired because acquisition provides an established customer base, experienced employees, licenses, relationships and revenue from the first day.
The company is no longer simply a local forwarder with overseas agents.
It has become a multinational forwarding company.
And every additional location potentially increases the value of the existing network.
A new office does not simply create one additional market. It creates new commercial relationships with multiple existing locations.
An office in Singapore can generate business with Germany. Germany can generate business with China. China can generate business with the United States. The United States can generate business with Singapore. The number of potential trade relationships grows as the network expands.
This is where the network itself starts becoming an increasingly important competitive capability.
Stage 6: Reach “Good”
Continue this process for 10, 20 or 30 years and the result can be a substantial mid-sized international freight forwarder.
Yet the organizational structure can remain surprisingly close to the model from which the company developed.
Most employees still contribute directly to generating, executing or managing business:
Sales → customer service → operations → customs → finance → local management
Corporate functions remain relatively lean.
There may be regional management, procurement, IT, finance, HR and product functions, but the company has not developed the extensive central structures associated with the largest global forwarding organizations.
The physical asset base can also remain relatively small compared with the revenue generated.
Warehouses, CFS facilities, large truck fleets and other capital-intensive infrastructure are generally provided by external specialists unless there is a specific strategic or economic reason for ownership.
Capital is instead concentrated primarily on people, offices, systems and network development.
The result can be an economically efficient forwarding organization with relatively low fixed-asset requirements.
It has become good at freight forwarding. It has experienced people. It has customers. It has reliable basic air and ocean freight capabilities. It has an international network. It has increasing purchasing power. And it has a business model capable of generating sustainable profits.
The Zero-to-Good Flywheel
The entire development model can be summarized as a freight-forwarding flywheel:
Win local customers
→ Generate export/import volume
→ Strengthen selected trade lanes
→ Develop stronger overseas partnerships
→ Receive routed business
→ Increase trade-lane density
→ Reach critical mass
→ Open or acquire an own office
→ Improve service, control and margin retention
→ Generate local business in the new market
→ Increase network volume and profitability
→ Reinvest profits into the next market
↺
Each turn of the flywheel strengthens the organization.
More customers create more freight.
More freight creates greater trade-lane density.
Greater density justifies greater network control.
Greater network control improves the product and creates new commercial opportunities.
Those opportunities generate additional profits that can finance the next stage.
There is therefore an important principle underlying the entire Zero-to-Good model:
Build the network behind the freight.
The company does not first construct an expensive international network and then hope enough freight arrives to support it.
The freight comes first.
The network follows.
Financing Growth From the Business
The financing model is an essential part of this strategy.
The company can choose to finance expansion primarily through profits generated by the existing business.
The logic is straightforward:
Business → profit → investment → additional capability → more business → more profit
The asset-light operating model makes this possible.
Because relatively little capital needs to be committed to warehouses, CFS facilities and other physical logistics assets, a greater proportion of available investment can be directed toward commercial and network development.
Profits can finance a new office. They can finance additional salespeople. They can finance systems. They can finance regional functions. They can contribute toward acquisitions.
And as those investments generate additional business and profit, further investments become possible.
But there is an unavoidable consequence.
The speed and size of investment are constrained by the profits the company generates.
A company cannot continuously invest substantially more than it earns without obtaining capital from somewhere else.
That means investments tend to happen progressively.
One market is developed. Then another. One capability is added. Then another.
The company grows within the financial capacity created by the existing organization.
A Constraint That Creates Discipline
At first glance, limiting investment to internally generated funds may appear to be a disadvantage.
And in one sense it is.
A company with access to substantial external capital could potentially expand faster.
It could acquire several companies simultaneously, enter multiple countries, build infrastructure or invest heavily in technology and organizational capabilities ahead of existing demand.
A self-financed company has fewer options.
But that constraint also creates discipline.
Every significant investment has to answer a fundamental question:
Does the existing or realistically accessible business justify this investment?
A new office cannot simply be opened because a market looks attractive on a strategy presentation.
A meaningful commercial case has to exist.
Expansion therefore tends to follow proven business rather than anticipated business.
This reduces the risk of building an expensive network that customers never fill.
Independence Has Value
There is another side to the financing model.
By relying primarily on internally generated profits, the company can preserve a high degree of financial and strategic independence.
It is less dependent on external investors seeking returns within a particular investment horizon.
It is less dependent on lenders imposing financial conditions on the business.
Ownership and management can therefore take a longer-term view.
A trade lane can be developed patiently. A market can take several years to mature. Customer relationships can be built over decades. Profits can be reinvested rather than maximized for short-term distribution.
The trade-off is therefore not simply:
More capital versus less capital.
It is:
Faster access to investment capital versus greater financial independence and control over the company’s long-term direction.
For a company moving from zero to good, that trade-off can work remarkably well.
From Zero to Good
None of this requires an especially complicated strategy.
In fact, its strength comes partly from its simplicity.
Win customers.
Execute their freight well.
Concentrate on trade lanes where you develop strength.
Build strong overseas partnerships.
Replace partners with owned operations when the business justifies it.
Remain asset-light where ownership does not create sufficient value.
Generate profits.
Reinvest those profits into the next stage of the network.
Then repeat.
Over many years, this can transform a small local forwarder into a substantial multinational forwarding company.
The company has built its network largely behind the freight, allowing proven business to determine where scarce investment capital should go.
The same discipline that limits the speed of expansion also protects the company from overextending itself and allows it to remain independent.
For the journey from zero to good, this can be an exceptionally effective model.
But success eventually creates a new problem.
The company reaches a size where simply repeating what worked before may no longer be enough.
Some of the capabilities required to attract larger customers, increase network density and compete at the next level may need to be built before the freight exists to justify them.
The investments may also become larger than those required during the company’s earlier development.
And suddenly the principles that helped build a successful, independent forwarder create a new strategic question:
How do you go from good to great when the next stage of growth requires investing ahead of the business rather than behind it?
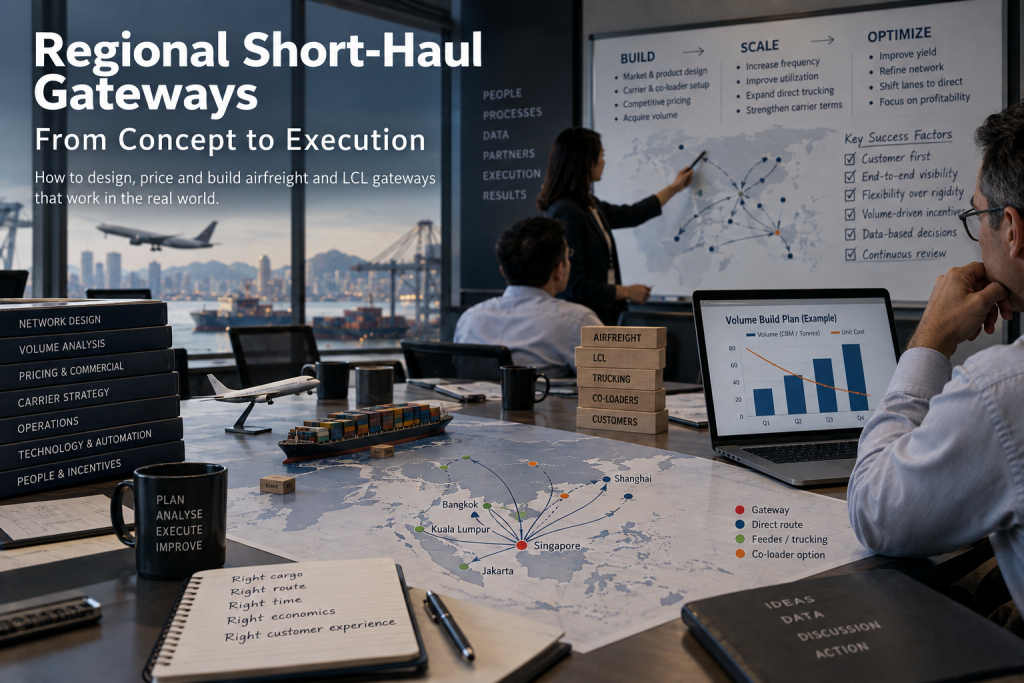
Gateway concepts are well established in freight forwarding.
Cargo from multiple origins is concentrated at a gateway, consolidated into larger movements and transported to destination. On long-haul trades, the logic is relatively straightforward. Consolidating volume creates buying power, improves capacity utilization and allows forwarders to build controlled products around major intercontinental trunk routes.
But can the same concept work for regional short-haul airfreight and LCL?
It can, but simply applying a traditional long-haul gateway model to regional trades is unlikely to produce the desired result.
Short-haul economics are different. Customers expect fast transit, direct transportation options are plentiful and departures can be frequent. A few hours of unnecessary handling can represent a significant percentage of the total door-to-door journey.
A successful regional gateway therefore needs to optimize:
Volume + Frequency + Transit Time + Capacity + Flexibility + Cost
That requires looking beyond consolidation itself. Physical handling, first-mile trucking, carrier policy, co-loaders, pricing, quotation speed and internal incentives all become part of the design.
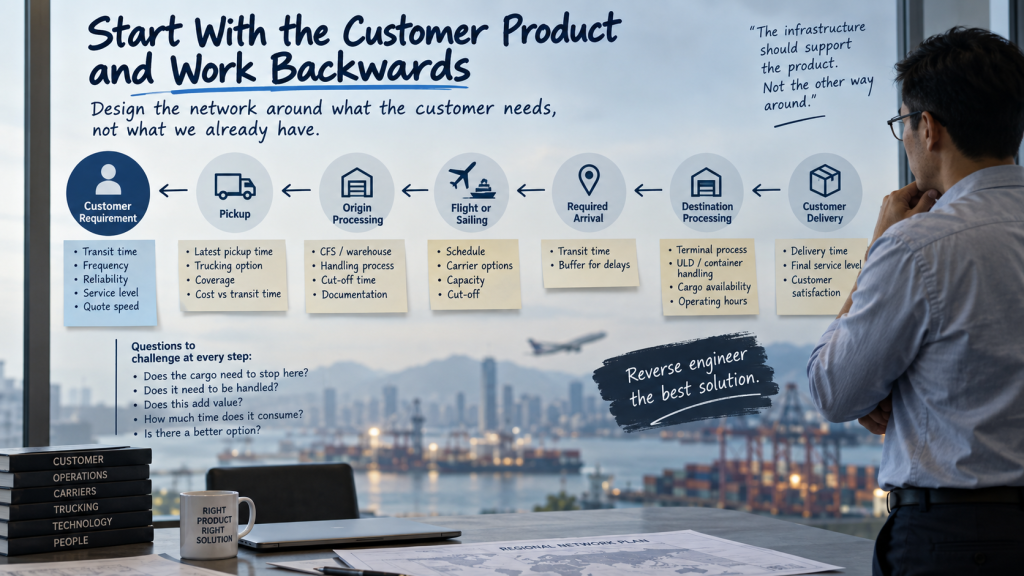
Most importantly, the starting point should not be the infrastructure the forwarder already has.
It should be the product the customer needs.
A common approach to gateway development is to begin with the existing organization.
We have these warehouses, handling partners, carriers, trucking providers and consolidations. How can we build a gateway around them?
For short-haul freight, I believe this should be reversed.
Start with the customer proposition.
What door-to-door transit time are we promising? How frequently must we depart? What reliability is required? What is the latest acceptable pickup time? How quickly must we quote?
Only then should the physical and commercial network be designed.
If an existing warehouse adds six unnecessary hours, question the warehouse. If the carrier policy prevents access to the required departures, change the policy. If the trucking network causes cargo to miss the intended consolidation, reconsider the trucking model.
The infrastructure should support the product. The product should not be compromised to accommodate the infrastructure.
Consider Intra-Asia airfreight.
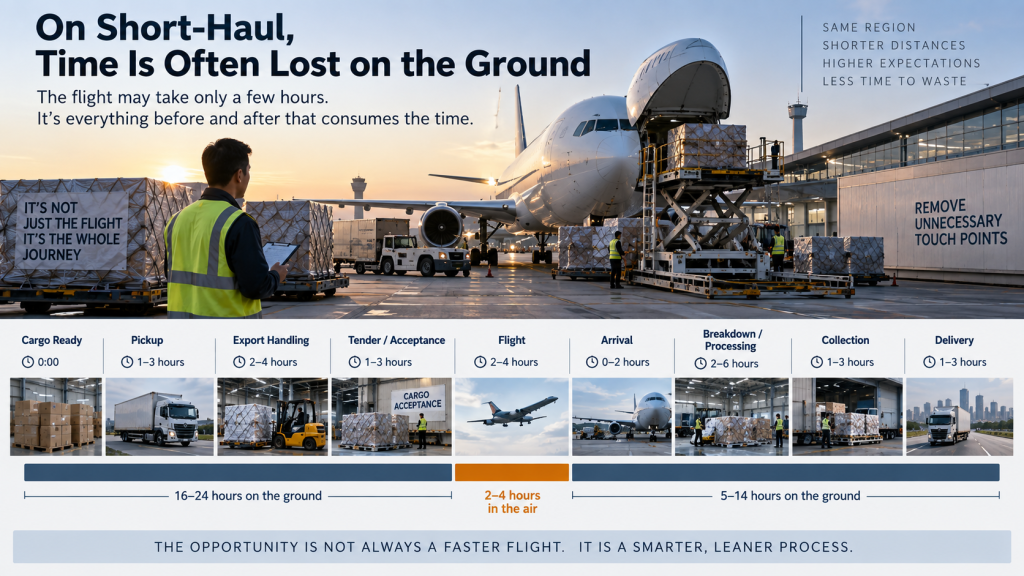
Customers may expect approximately one day door-to-door, with two days representing the upper end for many standard regional movements. Losing six hours somewhere in the process can therefore consume 25% of an entire 24-hour service window.
The flight itself may only take a few hours. The larger problem can be everything happening around it.
I have seen this first-hand on Singapore-Hong Kong airfreight movements. Cargo could arrive at the airport terminal in Hong Kong, be collected and then transported to another warehouse outside the airport for breakdown and processing. That additional movement could easily consume six hours.
Every physical touch point therefore needs to be challenged.
Does the cargo actually need to stop there? Does it need to be unloaded? Does it need to move to another warehouse? What value does the process add, and how much time does it consume?
The relevant measurement cannot simply be airport-to-airport transit. It needs to cover the complete journey:
Sometimes eliminating one physical cargo touch creates more customer value than negotiating another few percentage points from the freight rate.
Not every physical touch can simply be eliminated.
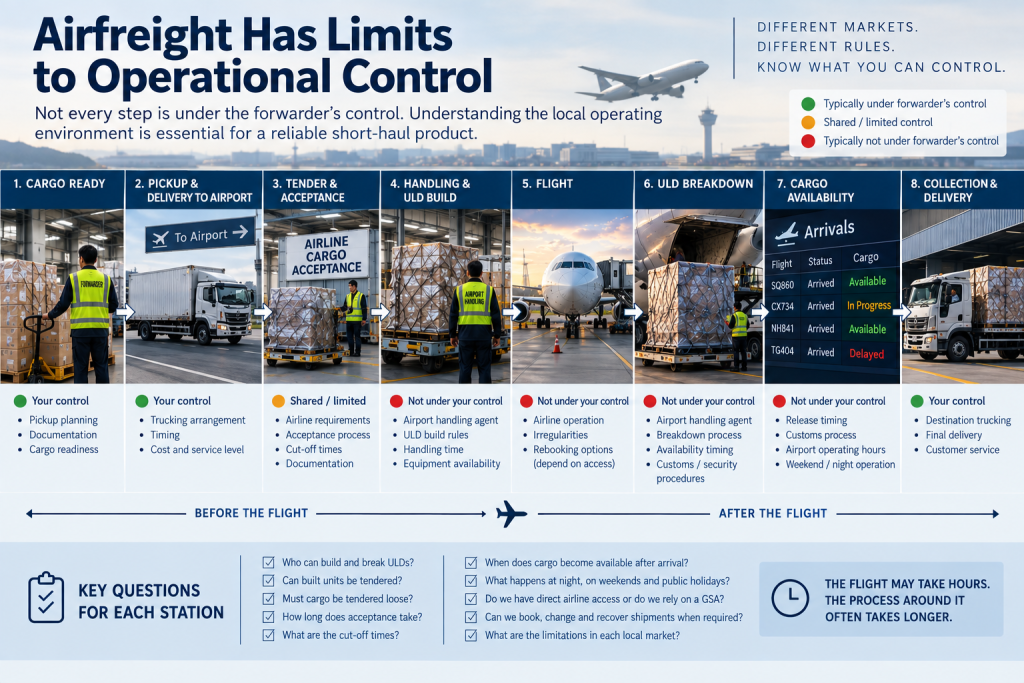
The ability of a forwarder to control cargo handling varies by market and airport. In some Asian operating environments, forwarders cannot independently build or break airline pallets or ULDs. Cargo may have to be tendered loose and collected loose after arrival.
Gateway analysis must consequently understand the actual operating environment at each location.
Who can build and break ULDs? Can built units be tendered? How long does acceptance take? When does cargo become available after arrival? What happens at night, on weekends and on public holidays?
Commercial access matters as well.
Forwarders without an IATA license that depend on GSAs, may have significantly less flexibility outside normal working hours.
That becomes critical when a shipment misses a Friday evening flight, additional capacity is required on Saturday or cargo needs to be switched to another carrier.
For short-haul airfreight, there are therefore three different forms of availability:
Schedule availability: The flight exists.
Commercial availability: Space and a rate are available.
Operational availability: The shipment can actually be booked, tendered, changed, recovered and collected within the required timeframe.
Only when all three are present is the flight genuinely useful to the gateway product.
A short-haul gateway cannot depend on infrequent consolidations.
If the underlying transportation takes one or two days but cargo waits three days for the next consolidation, the gateway has defeated the purpose of the product.
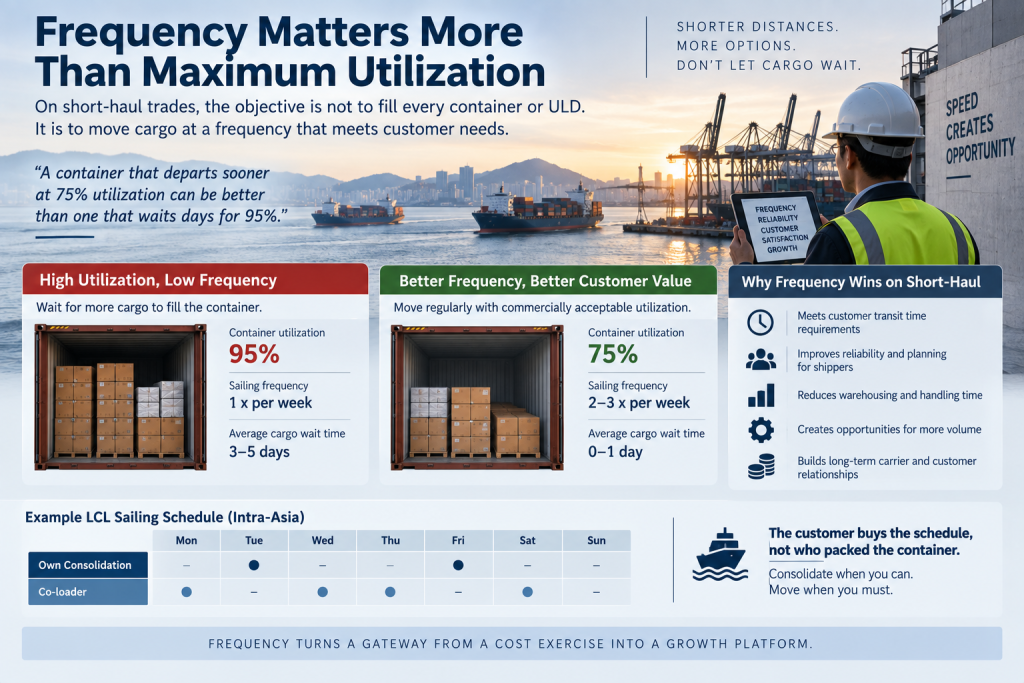
As a starting principle, a regional consolidation should probably offer at least two to three departures per week, with higher connectivity required on important time-sensitive corridors.
This creates a fundamental trade-off between utilization and frequency.
The objective should not be to maximize every ULD or container.
It should be:
Commercially acceptable utilization at a competitive frequency.
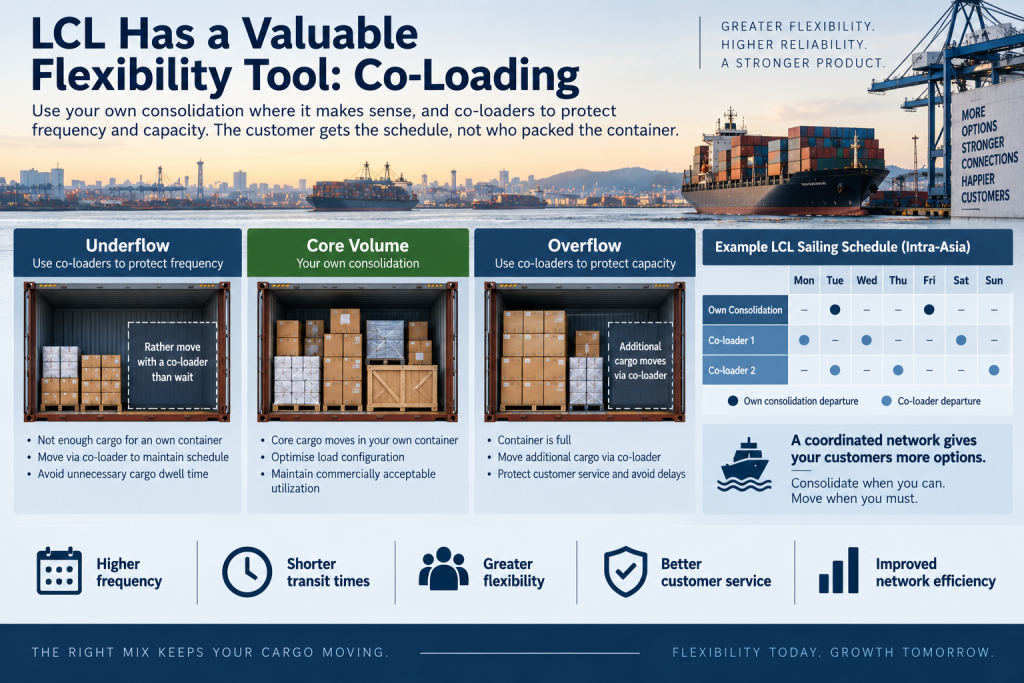
This is particularly important for LCL. On some intra-Asia corridors, several vessel sailings can be available within a single day. Holding cargo simply to achieve a fuller own container makes little sense if it damages the customer proposition.
A container departing at 75% utilization can be better than one departing at 95% if achieving the additional utilization requires holding cargo for several days.
LCL has an important advantage in solving this frequency problem.
The forwarder does not need to move every shipment in its own consolidation. Qualified co-loaders can be incorporated into the product to manage both underflow and overflow.
If insufficient cargo exists to justify the planned own container and waiting would compromise the service, cargo can move through a co-loader.
If the own container is full, additional cargo can also move through a co-loader rather than waiting for the next consolidation.
The model becomes:
Underflow → Co-loader protects frequency
Core volume → Own consolidation
Overflow → Co-loader protects capacity
This should not be treated simply as a temporary arrangement while the gateway develops. Co-loading can remain a permanent flexibility layer around the forwarder’s own consolidation programme.
The key is to coordinate sailing schedules.
If own consolidations depart Tuesday and Friday, selected co-loaders should ideally provide useful departures around those sailings rather than simply duplicating them.
The combined schedule could provide departures across most of the week even though only some are operated as own consolidations.
From the customer’s perspective, the product is the schedule, not who packed the container.
This leads to a useful operating principle:
Consolidate when you can. Move when you must.
Each shipment effectively has a maximum permissible dwell time. If the next own consolidation falls within that window, use it. If it does not, move the cargo through the best qualified alternative.
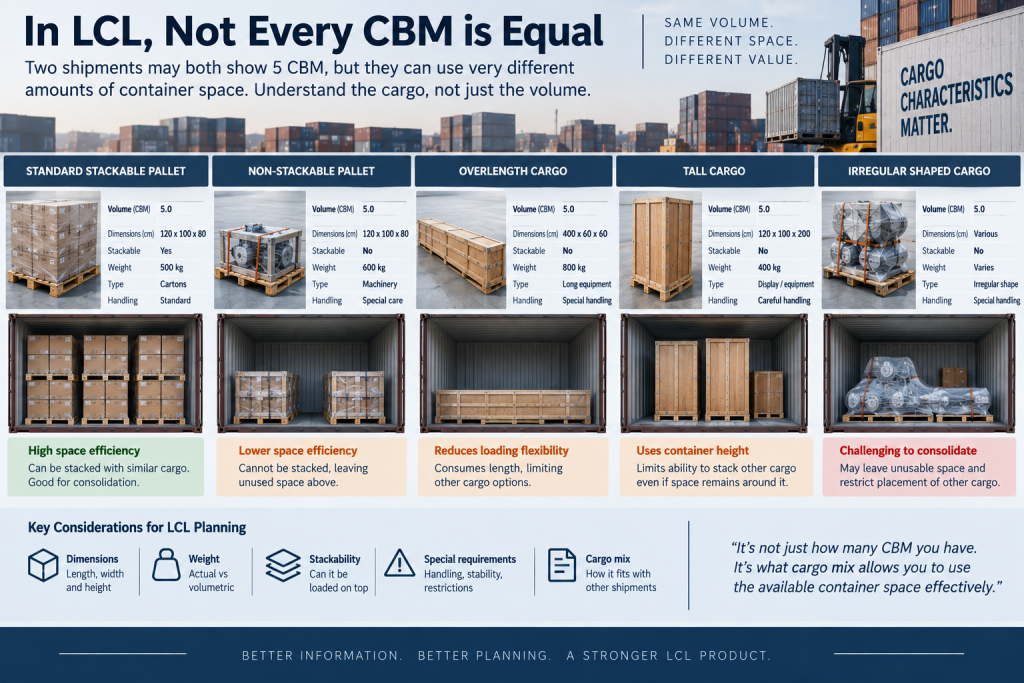
Volume analysis for LCL also needs to consider the physical characteristics of the cargo.
Cargo on relatively low pallets, for example around 80 cm high and safely stackable, is attractive consolidation cargo because suitable freight can potentially be loaded above it.
Non-stackable pallets, non-standard skids, overlength pieces, machinery, tall cargo and irregularly shaped freight are very different.
Two shipments may both show 5 CBM in the forwarding system while consuming completely different amounts of usable container capacity.
A non-stackable skid can leave substantial unused space above it. An overlength piece may prevent several other shipments from being positioned efficiently.
The gateway therefore needs to understand effective capacity, not simply booked CBM.
Dimensions, packaging type, stackability, weight and loading restrictions should form part of the analysis.
The important question is not simply:
How many CBM do we have?
It is:
What cargo mix allows us to use the available container space effectively?
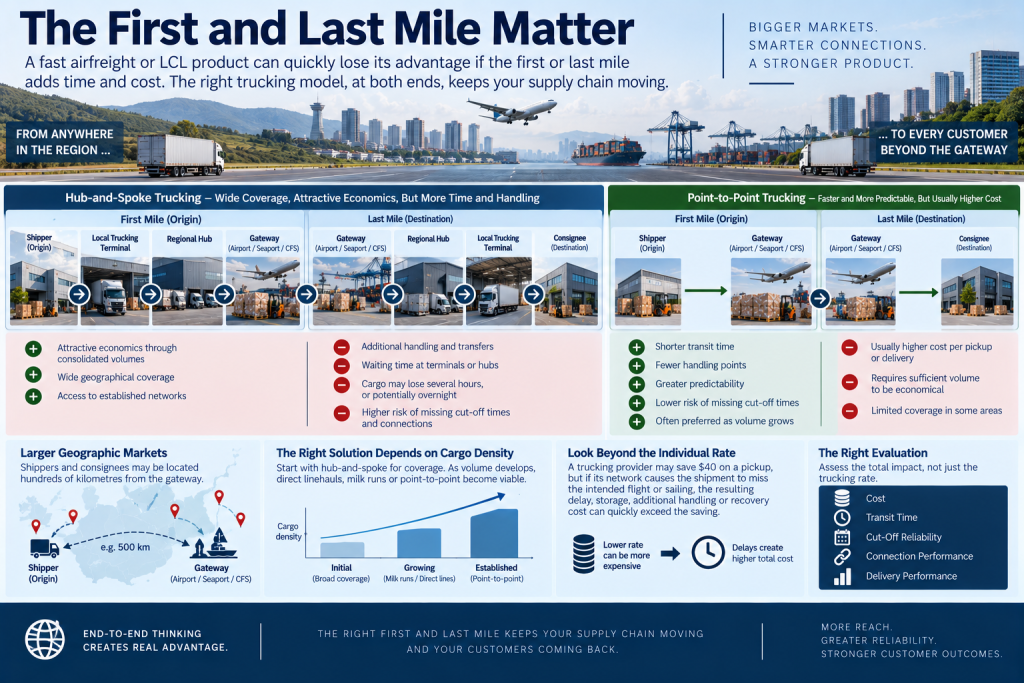
The same end-to-end thinking needs to include both first- and last-mile trucking.
This becomes particularly important in larger geographic markets where shippers and consignees may be located hundreds of kilometres from the gateway. A fast international airfreight or LCL product can quickly lose its advantage if significant time is added before departure or after arrival.
Large trucking companies often operate hub-and-spoke networks. On the first mile, the movement may look like:
Shipper → Local trucking terminal → Regional hub → Gateway
At destination, the process can effectively operate in reverse:
Gateway → Regional hub → Local trucking terminal → Consignee
These networks can provide attractive economics and broad geographical coverage because cargo from many customers is combined. However, every additional terminal introduces another transfer, handling activity and potential waiting period. Cargo may lose several hours, or potentially overnight, at either end of the international movement.
The alternative is a more direct trucking solution:
Shipper → Gateway
and
Gateway → Consignee
Point-to-point trucking can reduce handling, improve predictability and shorten door-to-door transit. The trade-off is cost. Without sufficient cargo density, direct trucking can be considerably more expensive than using an established hub-and-spoke network.
The appropriate solution therefore depends on both geography and volume.
During the early development of a gateway, hub-and-spoke trucking may provide the most economical way to achieve broad market coverage. As cargo density develops within particular regions, direct linehauls, milk runs or point-to-point trucking can become viable on either the origin or destination side.
This means first- and last-mile networks should evolve together with the gateway rather than being treated as fixed arrangements.
It also demonstrates why trucking procurement cannot be evaluated purely on the individual pickup or delivery rate.
A cheaper first-mile solution may cause cargo to miss the planned flight or sailing. A cheaper last-mile solution may add a day to delivery after the cargo has already reached the destination gateway. In either case, savings on the trucking rate can be outweighed by additional handling, storage, missed connections, recovery costs or deterioration of the customer proposition.
For a short-haul product, the international movement may only take a few hours or a day. The first and last mile can therefore determine whether the overall product is genuinely fast or merely appears fast on the flight or sailing schedule.
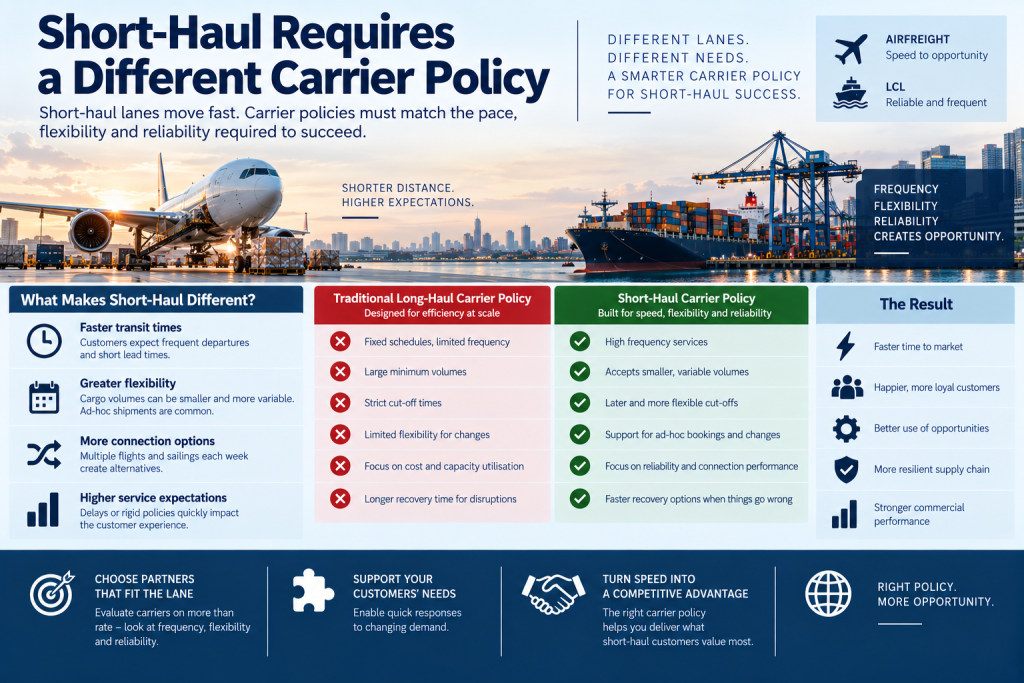
The same principle applies to carrier procurement.
Carrier concentration can make considerable sense on long-haul trades. Concentrating large volumes with selected carriers can generate attractive rates, capacity commitments and strategic benefits.
Rigidly applying the same philosophy to short-haul gateways can reduce the frequency and flexibility the product requires.
If five carriers provide useful departures but procurement policy effectively restricts the operation to one or two, the forwarder has voluntarily reduced the available network.
For short-haul traffic, the hierarchy should increasingly become:
Preferred carrier → Available departure → Customer service
This does not mean abandoning procurement discipline. It means recognizing that frequency, cut-off, recovery capability and operational flexibility have economic value.
Carrier interests can also align with this approach because carriers want volume.
Instead of discussing only today’s rate, procurement can approach carriers with a lane-development proposition based on expected recurring volume.
As the gateway grows, that volume creates greater buying leverage.
And this still requires the relationships with key GSA’s that occasionally offer attractive rates on specific flights.
This leads to perhaps the most difficult gateway question:
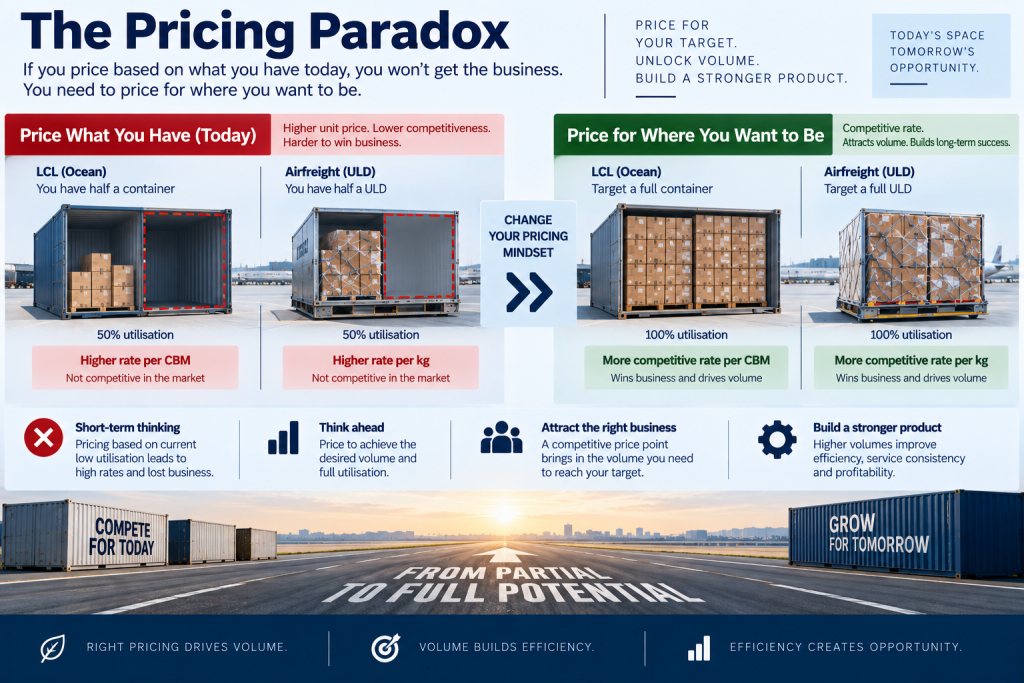
Do we price based on the volume we have today or the volume we intend to build?
Pricing purely on today’s low volume can create a self-defeating cycle:
Low Volume → High Unit Cost → High Selling Price → Low Conversion → Low Volume
The gateway may then fail not because the market was insufficient, but because its initial pricing prevented it from attracting the volume required to become competitive.
A better approach is to model the economics at different volume levels.
For example:
LCL: 20 → 40 → 60 → 80 CBM per week
Airfreight: 2 → 5 → 10 → 20 tonnes per week
At each level, calculate utilization, departure frequency, buying rates, handling costs and resulting unit cost.
This produces a gateway cost curve and identifies the critical-mass point at which the product becomes commercially sustainable.
Pricing can then be established against a target-volume business case rather than solely against today’s volume.
However, the difference between today’s actual cost and the competitive rate required to build future volume cannot simply be ignored.
It is an investment.
Management should explicitly identify:
Actual cost: The cost at current volume.
Target-volume economics: The expected cost at the planned level of activity.
Development gap: The investment required while moving between the two.
That gap should have an approved budget, volume milestones and a defined timeframe. If the expected volume does not materialize, the assumptions need to be revisited.
Volume First Changes the Incentive Model
The gateway development sequence is:
Volume → Frequency → Utilization → Buying Power → Profitability
That has a major implication for incentives.
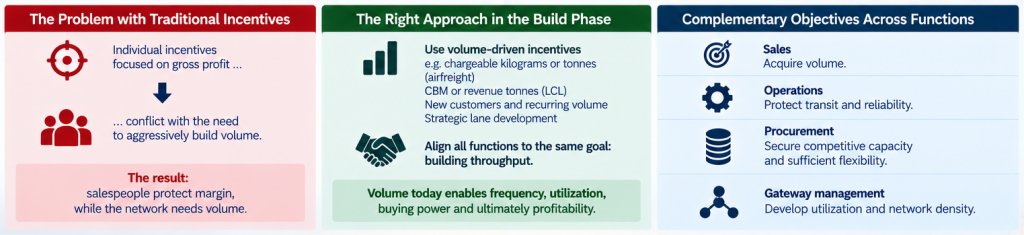
Classic freight forwarding profit-share models are poorly suited to the Build phase.
If salespeople are rewarded primarily on gross profit while management asks them to aggressively build a new gateway, the objectives conflict. The individual is encouraged to protect margin while the network needs volume.
During the Build phase, incentives therefore need to be volume driven.
For airfreight this could be chargeable kilograms or tonnes. For LCL it could be CBM or revenue tonnes. New customers, recurring volume and strategic lane development can also be recognized.
And this alignment cannot stop with sales.
Operations cannot be measured only on local station profitability if the objective is to build regional throughput. Procurement cannot be rewarded solely for preferred-carrier compliance if the product requires multiple carrier options.
The functions need complementary objectives:
Sales: Acquire volume.
Operations: Protect transit and reliability.
Procurement: Secure competitive capacity and sufficient flexibility.
Gateway management: Develop utilization and network density.
Profitability remains important, but expecting mature-gateway profitability while the network is still being built can prevent it from reaching maturity in the first place.
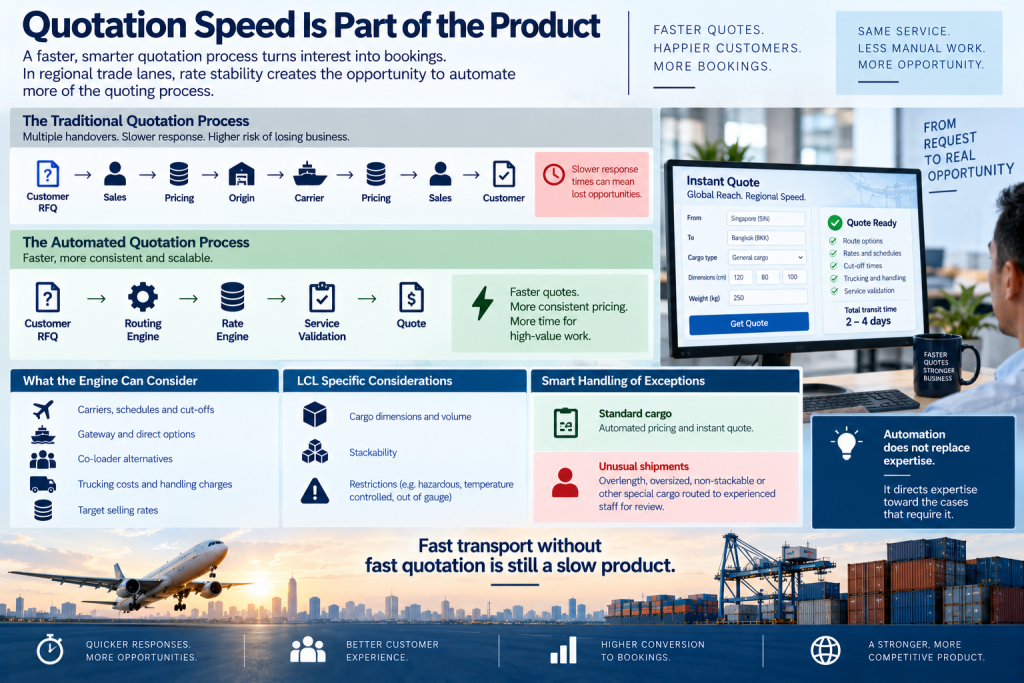
Another form of speed matters: quotation speed.
Regional rates can often be more stable than long-haul rates, creating an opportunity for greater automation.
The engine can consider carriers, schedules, cut-offs, gateway and direct options, co-loader alternatives, trucking costs, handling charges and target selling rates.
For LCL it can also consider cargo dimensions, stackability and restrictions.
Standard cargo can move through automated pricing, while overlength, oversized, non-stackable or otherwise unusual shipments become exceptions for experienced staff to review.
Automation does not replace expertise. It directs expertise toward the cases that require it.
Fast transport without fast quotation is still a slow product.
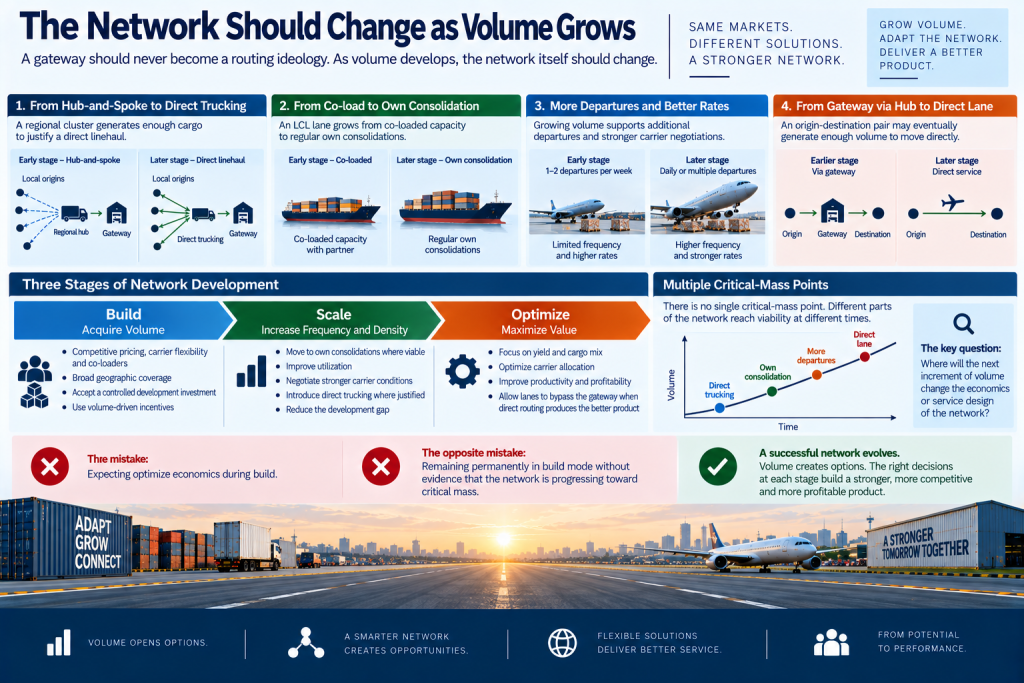
A gateway should never become a routing ideology.
As volume develops, the network itself should change.
A geographic cluster may generate enough cargo to replace hub-and-spoke trucking with a direct linehaul.
An LCL lane may generate enough volume to move from predominantly co-loaded capacity to regular own consolidations.
Growing gateway volume may support additional departures and stronger carrier negotiations.
Eventually, a specific origin-destination pair may generate enough cargo to move directly rather than through the gateway at all.
There is therefore no single critical-mass point.
There are multiple critical-mass points throughout the network, and each can trigger a different operational decision.
The important question becomes:
Where will the next increment of volume change the economics or service design of the network?
This naturally creates three stages of development.
Build
Acquire volume using competitive pricing, carrier flexibility, co-loaders and broad geographic coverage. Accept a controlled development investment and use volume-driven incentives.
Scale
Use growing cargo density to increase own-consolidation frequency, improve utilization, negotiate stronger carrier conditions, introduce direct trucking where justified and reduce the development gap.
Optimize
Once critical mass is established, place greater emphasis on yield, cargo mix, carrier allocation, productivity and profitability. Where individual lanes have developed sufficient density, allow them to bypass the gateway when direct routing produces the better product.
The mistake is expecting Optimize economics during Build.
The opposite mistake is remaining permanently in Build mode without evidence that the network is progressing toward critical mass.
Summary
Regional short-haul gateways can work, but they cannot simply be smaller versions of traditional long-haul gateways.
They need to be designed around the realities of short-haul transportation: limited tolerance for waiting, frequent transport options, different levels of operational control and a strong relationship between volume and service frequency.
Airfreight needs particular attention to terminal processes, ULD handling rights, airline access and out-of-hours flexibility.
LCL offers greater flexibility through coordinated own consolidations and co-loaders, but cargo characteristics and first-mile trucking can have a significant impact on effective capacity and transit time.
The commercial model is equally important. Pricing purely against today’s low volume can prevent the gateway from ever attracting the cargo required to become competitive. Building the product therefore requires a controlled investment against target-volume economics.
That also means classic profit-share incentives are inappropriate during the initial build. If volume is the strategic objective, incentives need to support volume.
The network can then evolve as cargo density develops:
Build → Scale → Optimize
The overall principle is simple:
Start with the customer product and work backwards.
Design the handling, trucking, carrier strategy, consolidation schedule, pricing and incentives required to deliver it. Then allow the network to change as volume reaches different critical-mass points.
And for short-haul LCL in particular, one operating principle captures the balance between consolidation economics and customer service:
Consolidate when you can. Move when you must.
Because in short-haul freight forwarding, improving transit time is often not about moving the cargo faster.
When a multinational manufacturing company reviews its freight forwarding activities, the discussion often starts with freight rates.
How much are we spending? Are our airfreight rates competitive? Should we consolidate volumes with fewer forwarders? Can procurement negotiate another five or ten percent?
Those are valid questions, but they address only a small part of the opportunity.
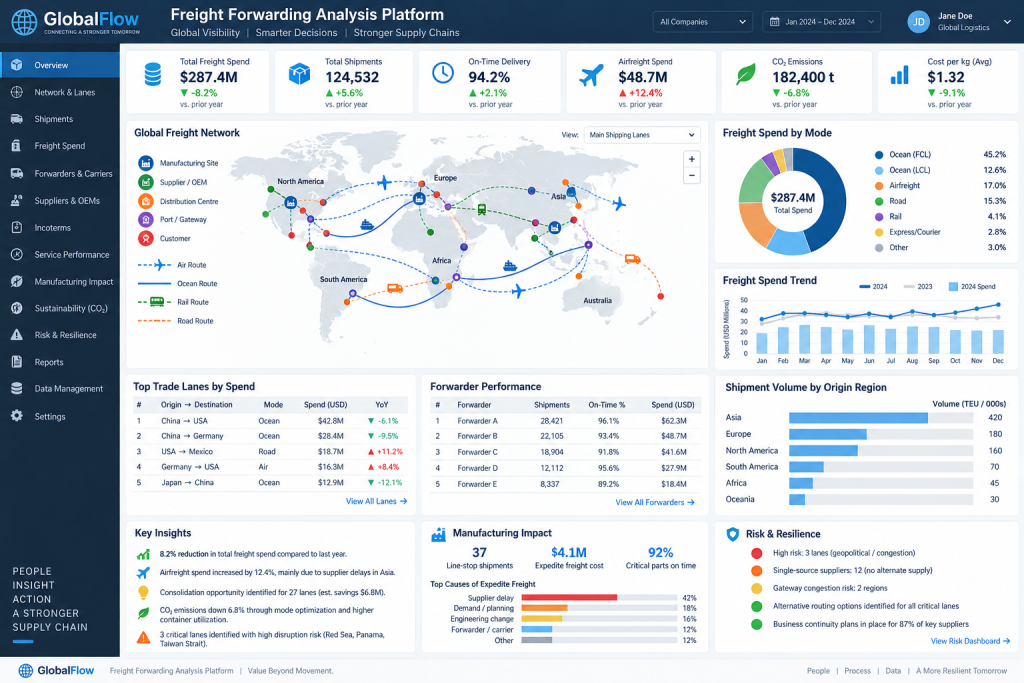
For a multinational with manufacturing plants across several countries, OEM or contract manufacturing partners, hundreds of component suppliers and customers around the world, freight forwarding is part of a complex network connecting procurement, production, inventory and customers.
A proper freight forwarding analysis therefore shouldn’t simply ask:
“Are we paying the right freight rate?”
It should ask:
“Is our freight network designed, controlled and operated in the most effective way to support the business?”
That is a much bigger question.
Start by understanding the network
Before looking at rates, the physical network needs to be understood.
Where are the manufacturing plants? Where are the OEMs and contract manufacturers? Where are the critical component suppliers? Which consolidation points, gateways and distribution centres are being used?
The next step is mapping the freight flows connecting them.
For each significant lane, the analysis should identify shipment frequency, volume, weight, mode of transport, forwarder, carrier, Incoterm, transit time and cost.
This sounds straightforward. In practice, multinational networks can become surprisingly fragmented.
Different plants may use different forwarders. Suppliers may control transportation under their own Incoterms. Local organizations may purchase spot freight outside global agreements. Several suppliers in the same region may ship separately to the same factory.
Until the network is mapped, management may not have a complete picture of how freight is actually moving.
Follow the money, but look beyond the freight rate
Freight spend should then be analyzed across multiple dimensions.
Spend can be broken down by manufacturing site, supplier, OEM, forwarder, carrier, mode, trade lane, business unit and region.
But base freight is only one part of the picture.
Fuel and security surcharges, terminal handling, customs clearance, pickup and delivery, storage, waiting time, demurrage, detention and other accessorial charges can materially affect the true transportation cost.
There is another important question:
How much freight spend is actually visible?
If suppliers sell components on delivered terms, transportation costs may be embedded in the product price. Procurement may therefore believe the company spends $50 million annually on freight when the real transportation expenditure across the supply chain is considerably higher.
This is where Incoterm analysis becomes important.
Changing the purchasing terms for selected suppliers may allow the manufacturer to take control of transportation, consolidate volumes and use its global purchasing power.
Analyze what is actually being shipped
Shipment-level data can reveal opportunities that rate negotiations never will.
How frequently are shipments moving? What is the average shipment size? How well utilized are containers? How much LCL traffic could potentially become FCL? Are multiple suppliers shipping independently from the same origin region to the same manufacturing facility?
Consider five suppliers around Shenzhen shipping components independently to the same European plant several times each week.
The organization could negotiate better rates for those individual shipments.
Or it could ask a more fundamental question:
Why are we moving five separate shipments in the first place?
Supplier consolidation, buyer’s consolidation, milk runs, regional gateways or consolidation centres may reduce shipment frequency, improve utilization and lower overall logistics cost.
That is network optimization rather than freight procurement.
Understand why premium freight happens
Airfreight and express shipments deserve particular attention in manufacturing environments.
Not all airfreight is bad. Some products genuinely require it because of value, lead time, shelf life or production requirements.
The more interesting question is how much airfreight was planned and how much was an emergency.
A component might have been shipped by air because the supplier produced it late. Another shipment might have resulted from inaccurate forecasting. A factory may have changed its production schedule. Engineering may have changed a specification. A forwarder may have missed a sailing.
These situations all appear in the freight data as expensive transportation.
But transportation isn’t necessarily the cause.
Premium freight should therefore be classified by root cause, for example:
Instead of saying, “Airfreight increased by $2 million,” the company can determine why it increased and which function needs to address it.
Measure freight performance against manufacturing requirements
Traditional logistics KPIs remain important.
Pickup reliability, booking confirmation, departure reliability, transit time, arrival reliability, customs clearance, POD availability and exception response should all be measured.
But manufacturing requires another layer.
Which shipments threatened production?
How many expedites occurred?
How much premium freight was incurred?
How many shipments resulted from supplier failure?
How often was production at risk because a critical component wasn’t available?
A $15,000 emergency airfreight shipment looks expensive when viewed by procurement.
If that shipment prevents a production line from stopping and avoids a much larger financial loss, it may have been the correct decision.
The question then becomes why the emergency shipment became necessary.
Analyze the suppliers as well as the forwarders
Forwarders are frequently measured through KPIs. Suppliers often receive less logistics scrutiny.
Yet supplier behavior can have a major impact on transportation performance.
The analysis should examine whether suppliers provide bookings on time, have cargo ready as agreed, provide accurate documentation, comply with packaging requirements and provide reliable shipment information.
The same applies to OEM and contract manufacturing partners.
This makes it possible to distinguish between a forwarder performance problem and an upstream supply-chain problem.
Review the processes behind the shipments
The next layer is process.
How does a purchase order eventually become a shipment?
The process can be mapped from:
PO → supplier readiness → transport order → booking → pickup → export clearance → main carriage → import clearance → delivery → POD → freight invoice → payment
Different factories within the same multinational often handle these processes differently.
One location may automatically transmit transport orders to a nominated forwarder. Another may email spreadsheets. A third may allow suppliers to make bookings directly.
These differences create cost, visibility and control problems.
Standardizing the right processes can therefore produce benefits that have nothing to do with negotiating freight rates.
Determine whether the data can actually support decisions
A sophisticated forwarding strategy cannot compensate for poor data.
The analysis should examine ERP, TMS, supplier portals, forwarder systems and EDI/API connections.
Ideally, the organization should be able to connect:
Purchase Order → Shipment → Transport Order → Forwarder → Freight Invoice → Product/Customer
When those connections don’t exist, answering seemingly simple questions becomes difficult.
Which product generates the highest freight cost?
Which suppliers generate the most premium freight?
Which manufacturing plant has the highest logistics cost relative to production?
Which forwarder is creating the most exceptions?
Which lanes have the greatest consolidation potential?
Data quality is therefore part of freight optimization.
Examine risk and resilience
Cost and performance aren’t the only considerations.
A global manufacturing network may depend on a single supplier, gateway, carrier, airport, port or transportation mode.
Critical lanes should therefore be examined for alternative routings, carriers, forwarders and modes.
The cheapest solution isn’t necessarily the right solution if a disruption can stop production.
The objective is to understand where resilience is required and where redundancy simply adds unnecessary cost.
Finally, look at governance
Perhaps the most revealing question in a multinational freight analysis is:
Who actually controls transportation?
The answer may be global procurement.
Or regional logistics.
Or individual factories.
Or suppliers.
Or OEMs.
Frequently, it is some combination of all of them.
The company may have global forwarding agreements while individual sites continue purchasing transportation locally. Suppliers may ignore nominated forwarders. Spot shipments may bypass contracted rates. Business units may maintain their own processes.
A forwarding strategy only works when governance supports it.
Clear ownership, tender processes, allocation rules, escalation procedures, KPI reviews and compliance monitoring are therefore as important as the freight contracts themselves.
Summary
A comprehensive freight forwarding analysis should ultimately provide management with visibility across four areas:
Cost: Are we buying freight efficiently?
Network: Are we moving freight efficiently?
Performance: Is transportation reliably supporting manufacturing and customers?
Control: Do we actually understand and control the freight network?
The analysis should connect suppliers, OEMs, factories, gateways, distribution centres and customers and attach meaningful information to each major freight flow:
Volume + frequency + mode + forwarder + carrier + Incoterm + transit time + performance + cost + risk
Most importantly, it should establish root causes.
If premium freight is increasing, why?
If freight costs at one plant are significantly higher, why?
If delivery performance is poor, is the problem the forwarder, carrier, supplier, planning process or manufacturing operation?
This is where freight forwarding analysis becomes much more valuable than a rate exercise.
A freight tender may tell a company whether it can buy transportation more cheaply.
A proper freight forwarding analysis tells management whether the company should be moving the freight that way in the first place.
There are various use cases for an enterprise digital twin.
One use case is to understand the workload and identify bottlenecks within the operations department.
Maybe you are familiar with this scenario. You are the GM of a Freight Forwarder and your Operations Manager comes to you and says our LCL Export department is collapsing. There are too many jobs and they are doing overtime every day. The team is alright with the overtime pay but the OM is worried what would happen in case one of the operators falls sick. He is also not able to approve any leave. He requests for extra manpower.
Asking for additional manpower means checking budgets, checking revenue and GP, checking productivity levels of the staff, and speaking to sales if this additional job load is permanent or seasonal. If the case for more manpower is justified, we then need to make a business case to management.
What if you had a digital twin of your department which would actually show which department is stretched and to what point. And you could see this before your OM raises the alarm. Usually by the time operations raises issues to management, the house is already burning – at least that’s my experience.
The identification of bottlenecks and workload issues is therefore one use case of an enterprise digital twin.
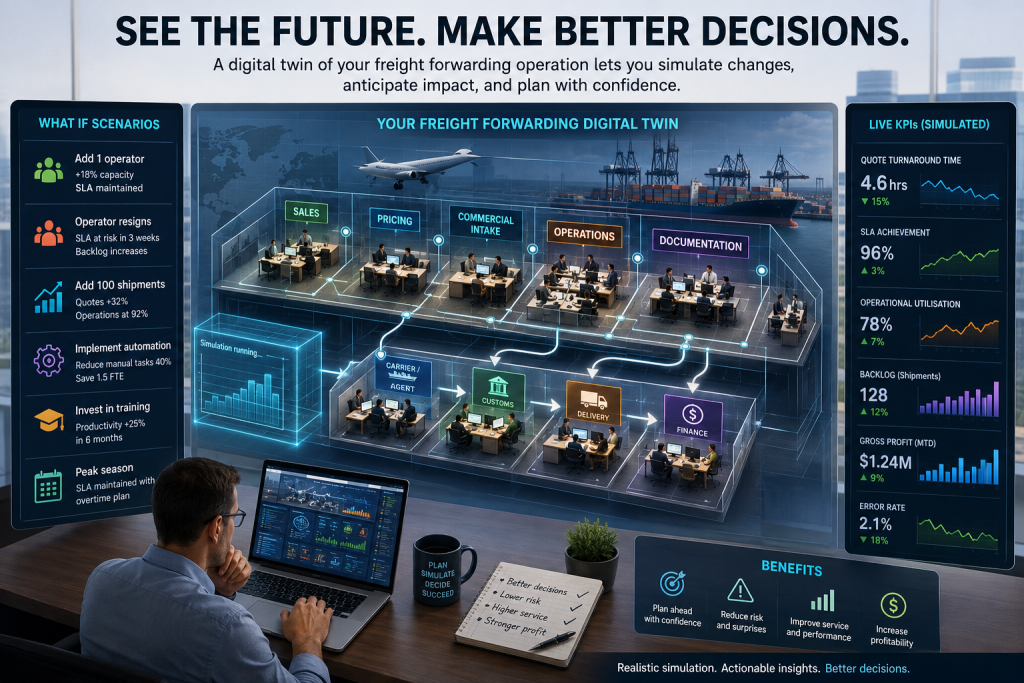
A digital twin is a virtual model of a physical product, process or business. In freight forwarding, a digital twin simulates the day-to-day operation of a branch or an entire company, allowing management to test decisions before implementing them in the real business.
Traditionally, operational decisions are based on experience, intuition and historical reports. While experienced managers develop a good instinct, they still have no way of accurately predicting the consequences of a change before it happens. A digital twin changes that by providing a safe environment in which different scenarios can be tested and their operational and financial impact measured.
One of the most valuable applications is workforce planning. What happens if an additional sales executive brings in another 100 shipments per week? Can the existing operations team absorb the workload, or will turnaround times and service levels begin to deteriorate? Conversely, what happens if one experienced operator resigns, goes on extended medical leave or takes annual leave during peak season? How long can the department continue operating before service levels start to fail?
Most companies only recruit after problems have already appeared. By the time shipments are delayed, overtime becomes excessive and customer complaints increase, the business is already reacting rather than planning. A digital twin allows management to identify these risks months in advance and build business cases for additional headcount based on simulated outcomes rather than assumptions.
The simulator can also evaluate automation projects before any investment is made. Instead of asking whether a solution sounds promising, management can measure its actual impact. For example, could a rate management platform eliminate the need for a dedicated pricing desk? Would an operational compliance solution reduce enough manual checking to avoid hiring another compliance officer? Could document automation reduce quotation turnaround times sufficiently to increase conversion rates? Rather than relying on vendor claims, the digital twin allows competing solutions to be tested against the same operational environment.
Another important application is bottleneck identification. Freight forwarding processes are highly interconnected, and improvements in one department often shift the bottleneck elsewhere. If quotations are completed twice as fast, does the operations department become overloaded? If customs declarations are automated, does documentation become the new constraint? A digital twin makes these dependencies visible before changes are implemented.
Customer mix is another area where simulation provides valuable insight. Two customers generating the same revenue may create completely different workloads. For example, one customer shipping ten containers on a single Bill of Lading requires significantly less operational effort than ten different customers each shipping one container with separate documentation, communication and billing requirements. Revenue alone does not determine workload, and a digital twin helps quantify these differences.
The platform can also evaluate service performance during seasonal peaks. Can the organisation continue meeting its promised service level agreements during periods of high demand? At what utilisation level does overtime become excessive? Which department reaches capacity first? Understanding these thresholds allows management to prepare resources before peak seasons begin instead of responding once delays occur.
A digital twin also highlights the hidden financial impact of operational delays. Consider a situation where an overseas network office consistently provides destination charges after 48 hours instead of 24 hours. The delay may appear insignificant, but its downstream consequences can be substantial. Quotations are delayed, response times increase, conversion rates decline, customers approach competitors, and operations receive work later than planned. By simulating these effects, management can quantify the true cost of slow internal processes and justify improvements with measurable data.
The digital twin can also be used to measure the return on investment of training and employee development. Every operator can be assigned an experience level, which directly influences productivity, error rates, decision quality and the amount of supervision required.
For example, what happens if a junior export operator with six months’ experience replaces a senior operator with ten years’ experience? How much additional workload is created for the rest of the team? How long does it take before the new employee reaches full productivity? Is it more cost-effective to hire an experienced operator or invest in training an existing employee?
The simulator can also evaluate different training strategies. What is the operational impact if every employee receives two days of training per quarter? Does the temporary reduction in capacity result in higher long-term productivity? Which teams generate the greatest return from additional training?
Instead of viewing training purely as a cost, management can quantify its effect on operational capacity, service quality, error rates and profitability, making investment decisions based on measurable outcomes rather than assumptions.
Other practical scenarios include:
Evaluating the impact of opening or closing a branch.
Assessing whether a new product or trade lane can be supported with existing resources.
Determining the effect of centralising pricing or documentation functions.
Measuring the operational impact of winning or losing major customers.
Testing different organisational structures before implementing them.
Comparing the return on investment of hiring additional staff versus investing in automation.
Ultimately, a freight forwarding digital twin transforms operational planning from reactive decision-making into evidence-based management. Instead of asking, “Do we think we need another person?”, managers can ask, “What will happen to utilisation, turnaround times, customer service, profitability and workload if we hire one more operator, lose one team member, introduce automation or win a major customer?”
The difference is no longer opinion versus opinion. It becomes measurable outcomes before real money is spent and before customers are affected.
Like many small business owners, I faced a problem.
I needed accounting, but I wasn’t large enough to justify a full-time accountant.
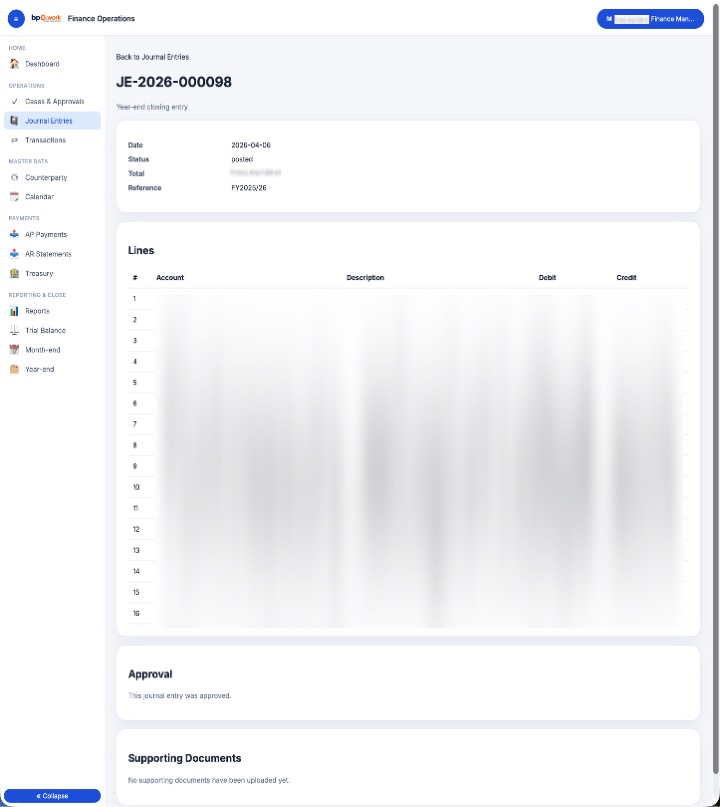
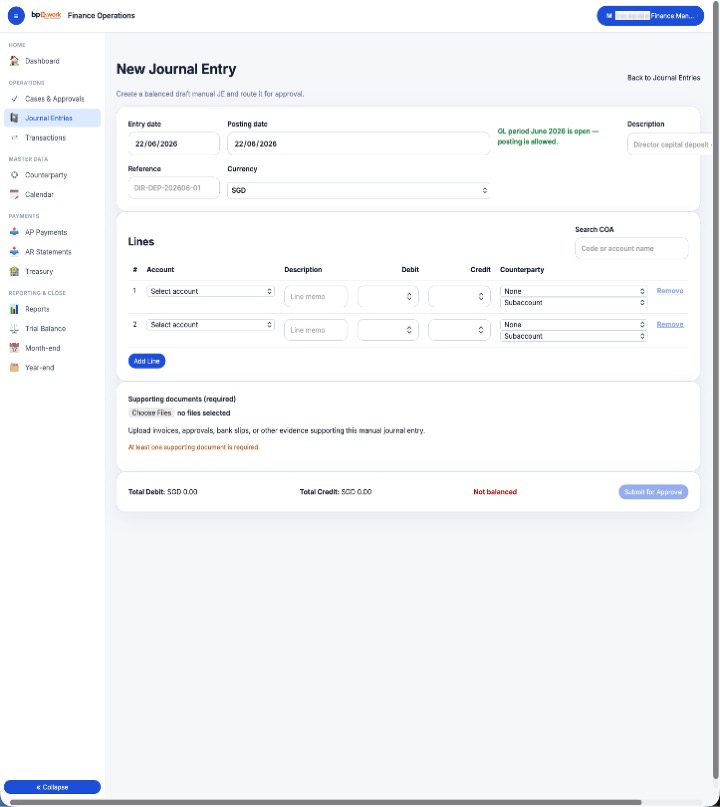
I also didn’t want to spend my evenings processing invoices, reconciling bank accounts, chasing receipts, preparing month-end journals, and dealing with year-end close.
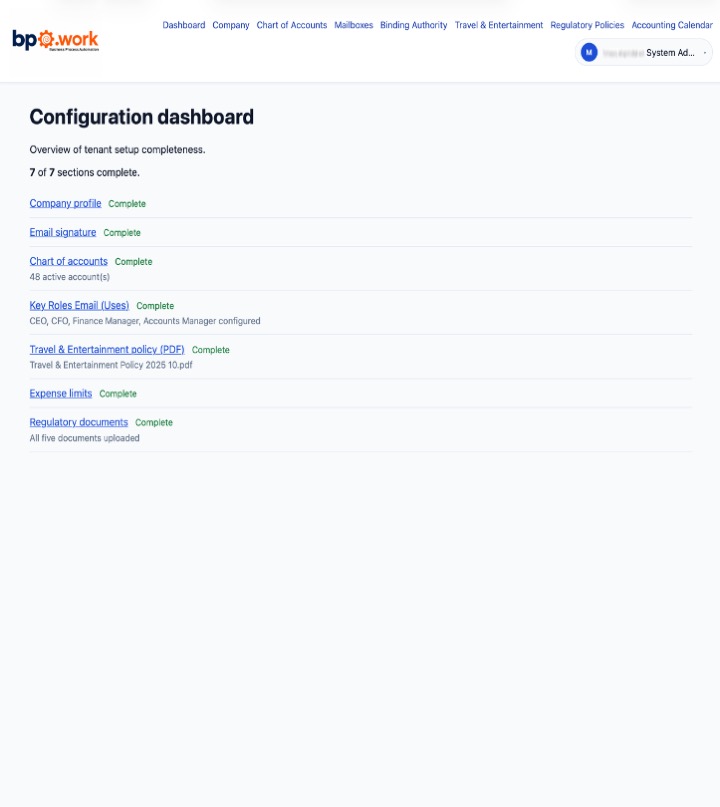
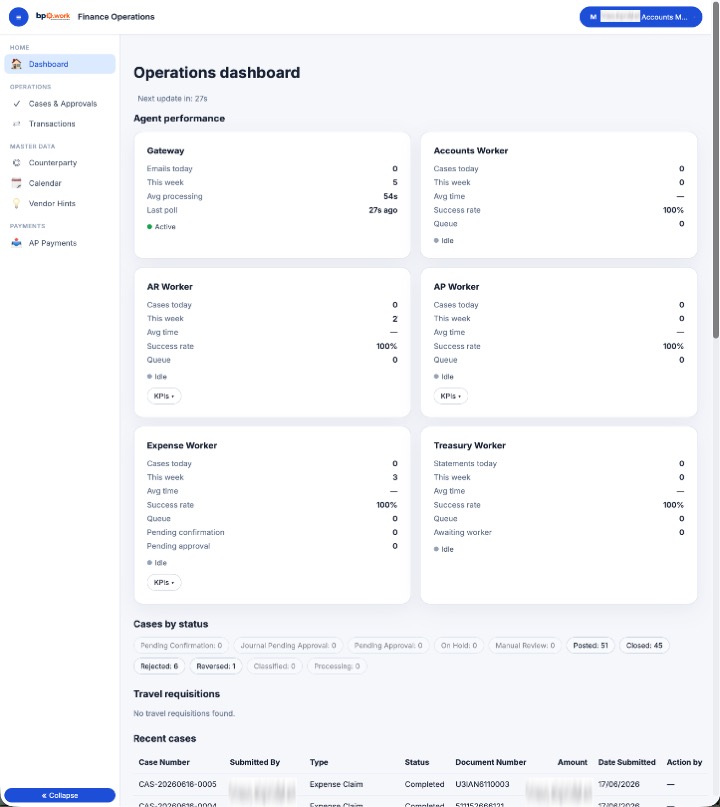
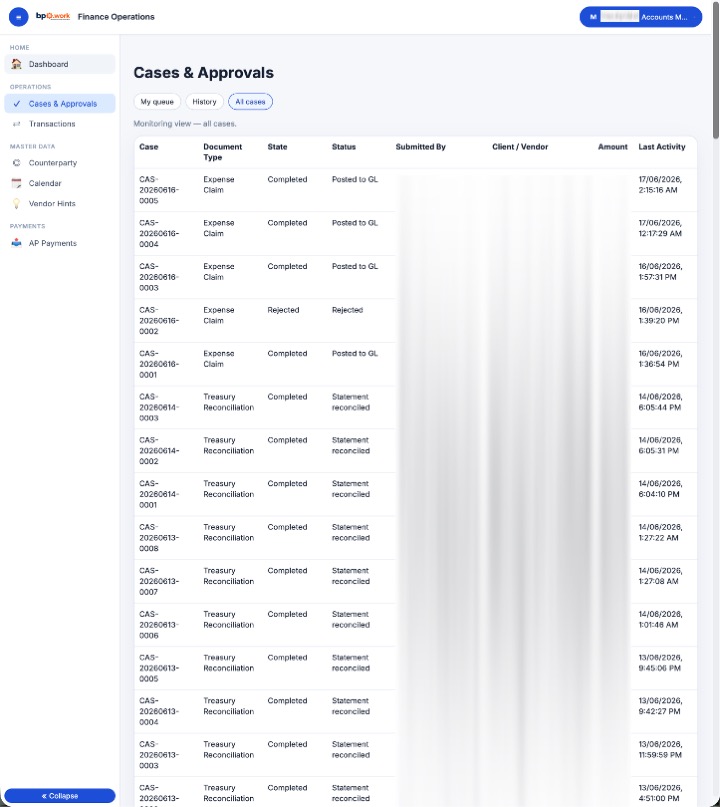
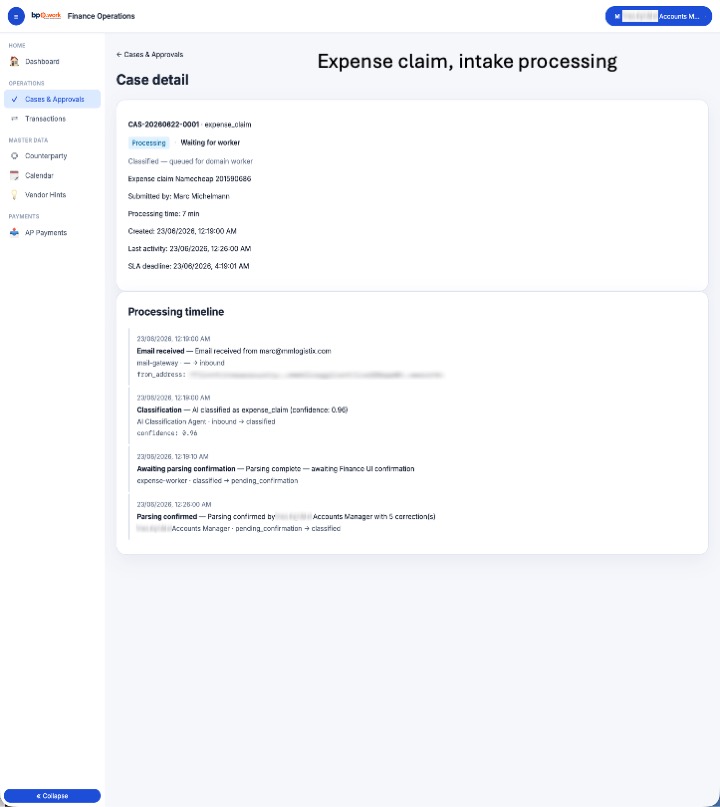
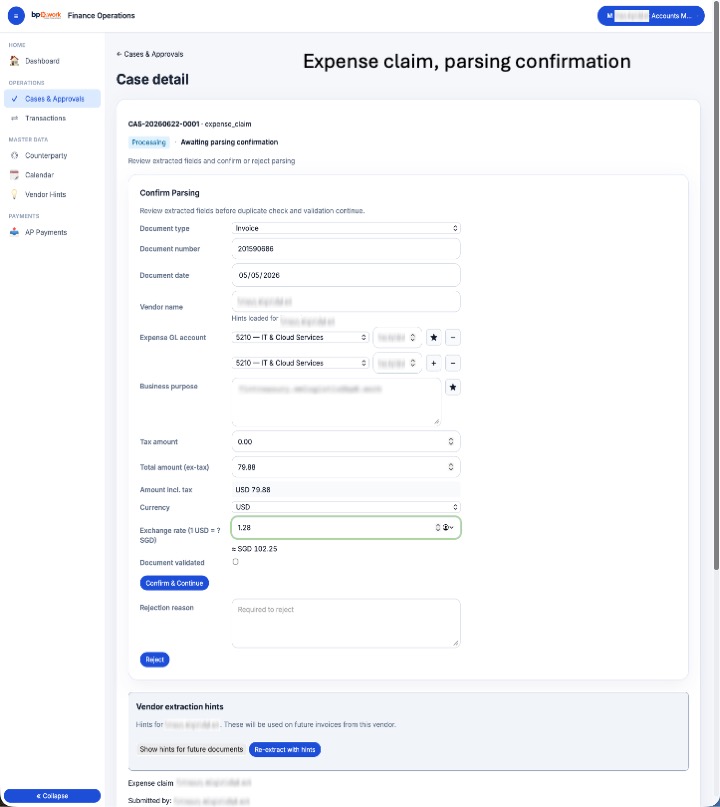
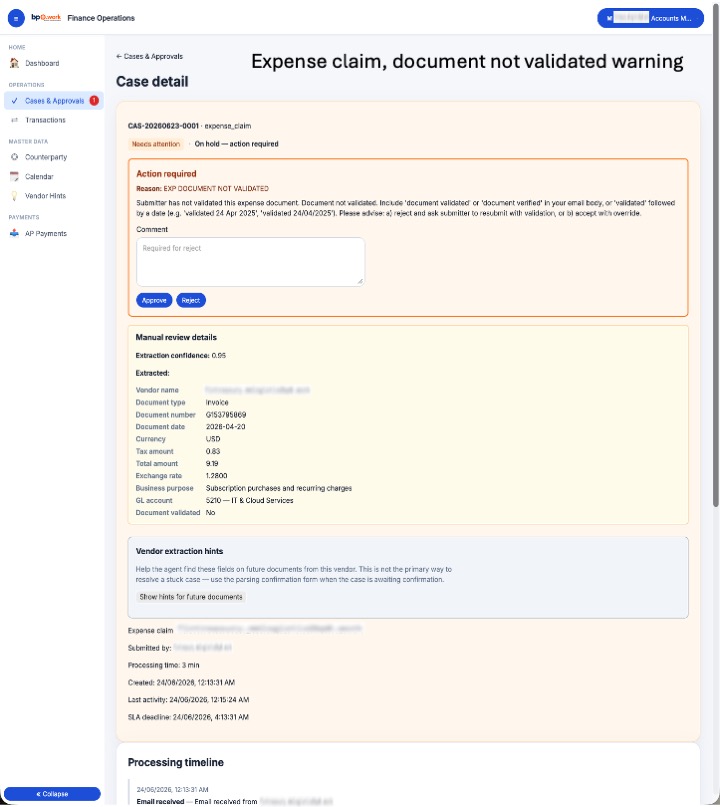
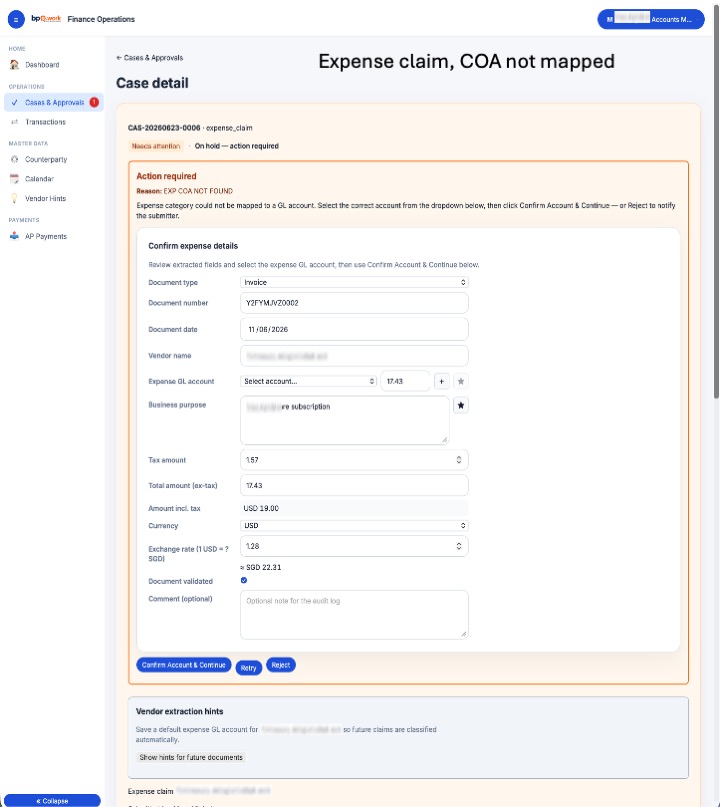
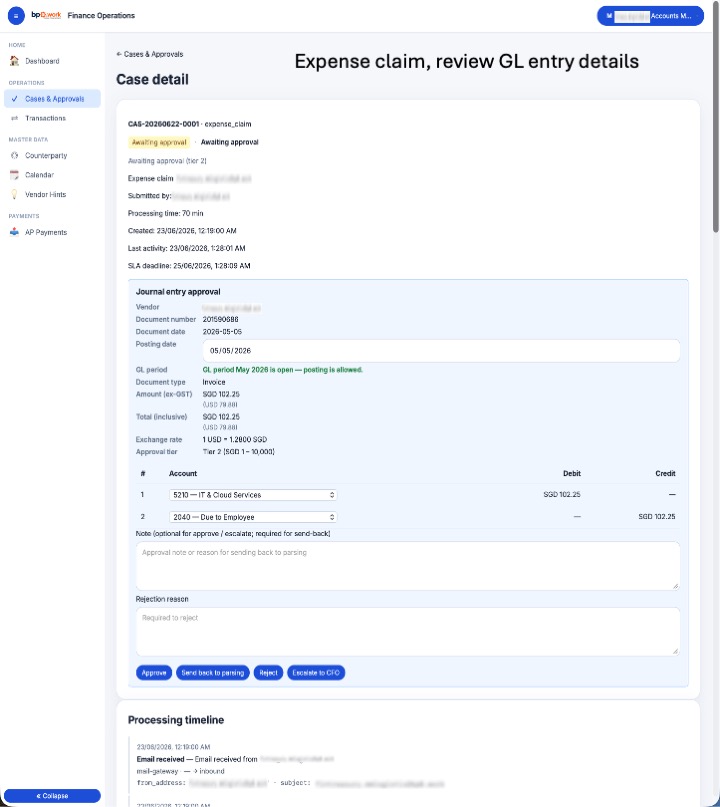
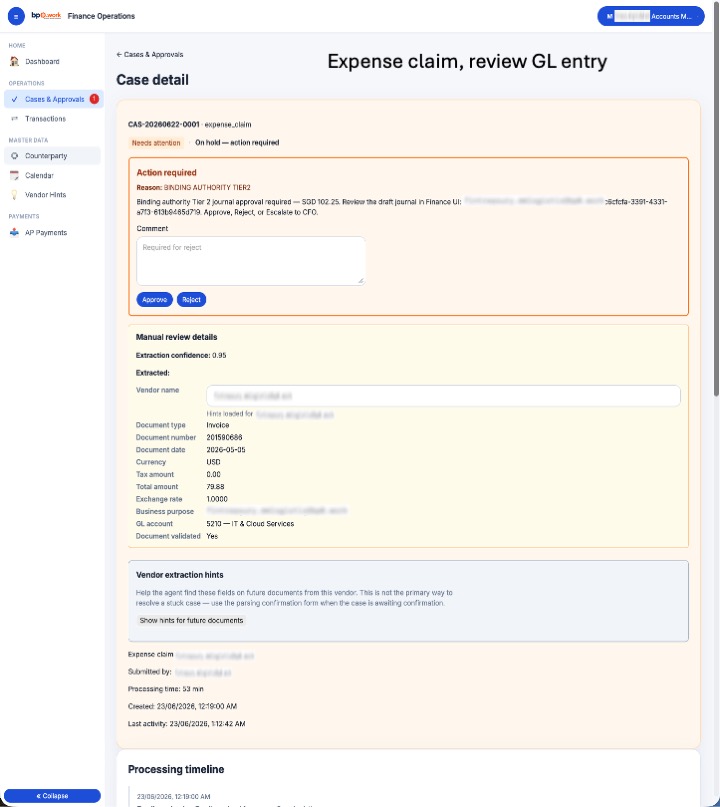
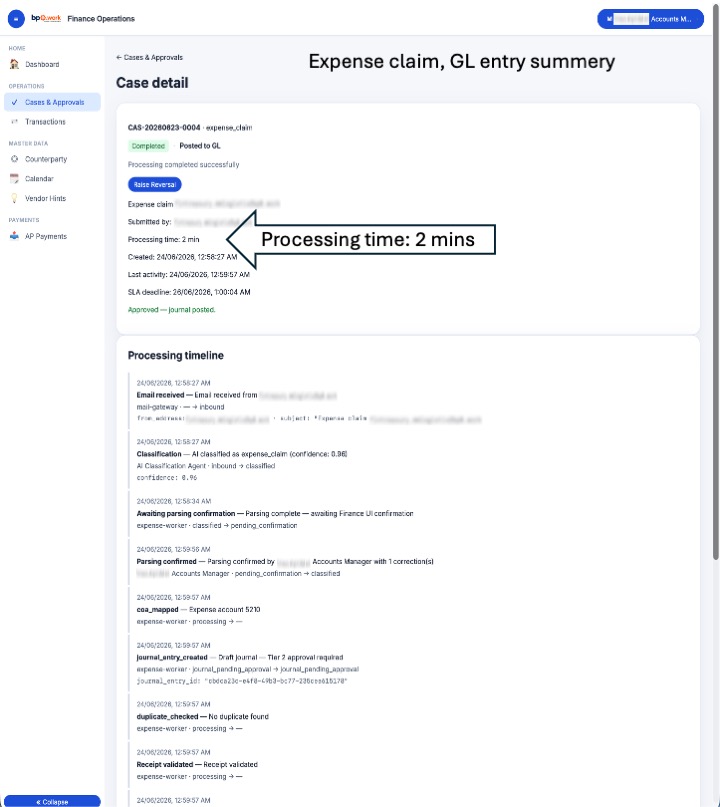
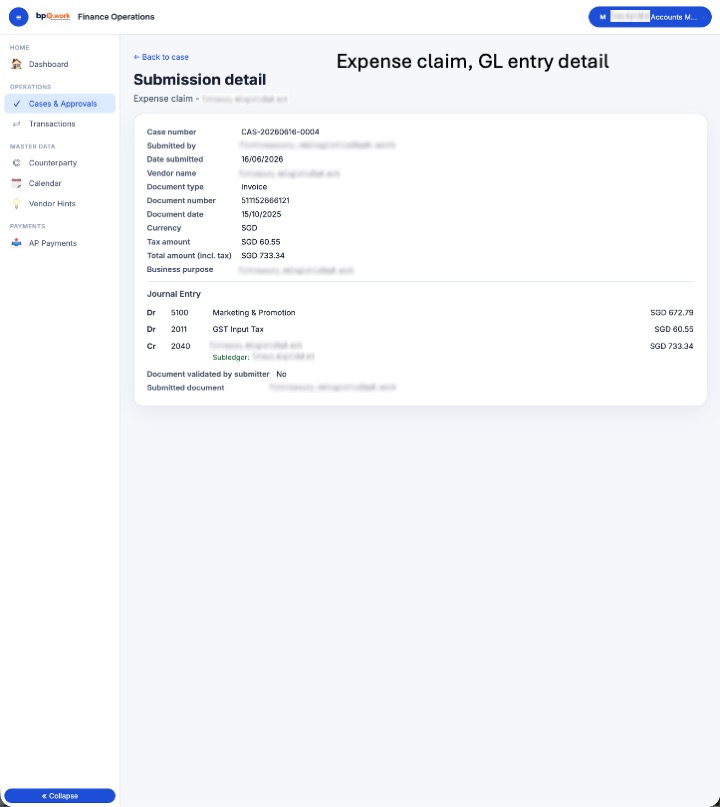
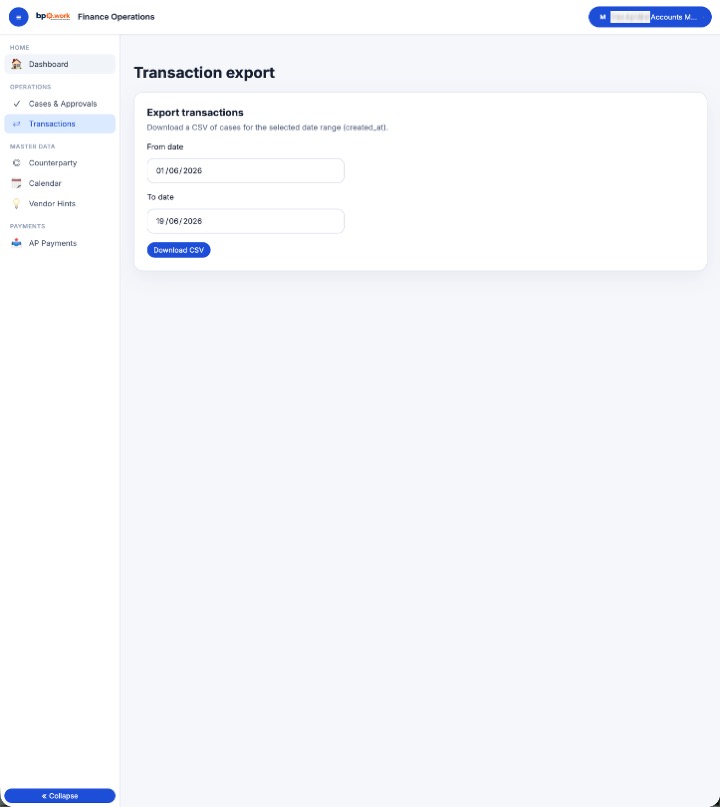
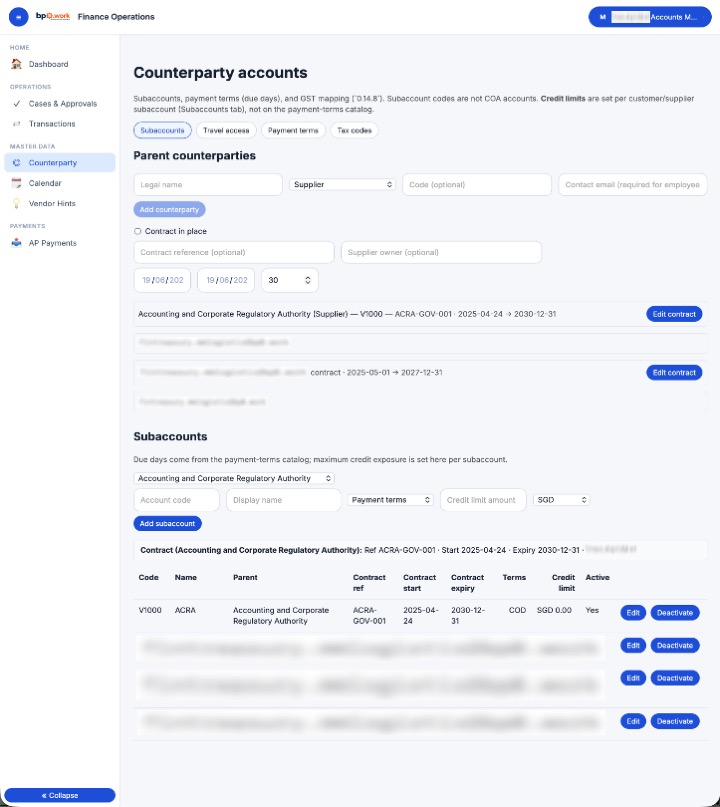
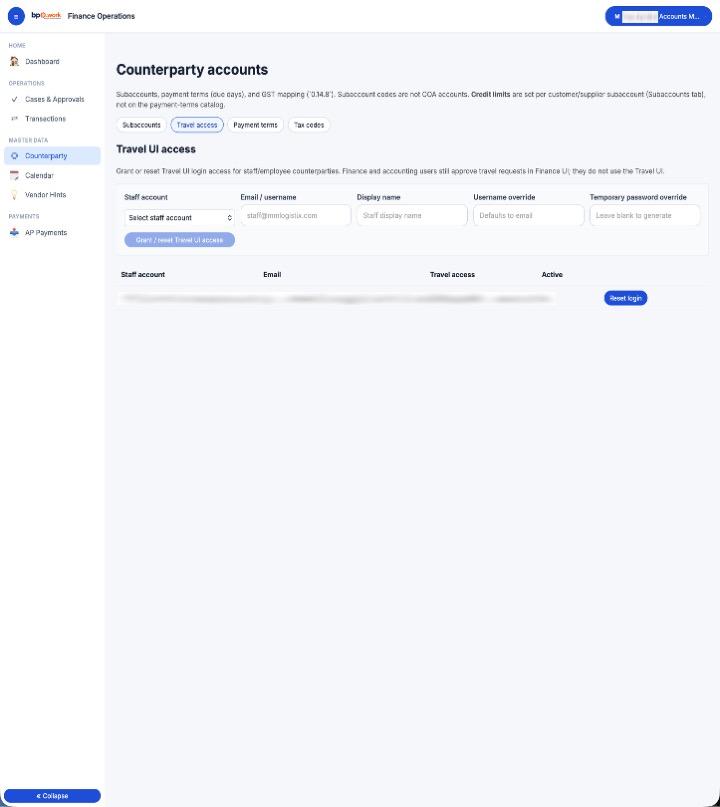
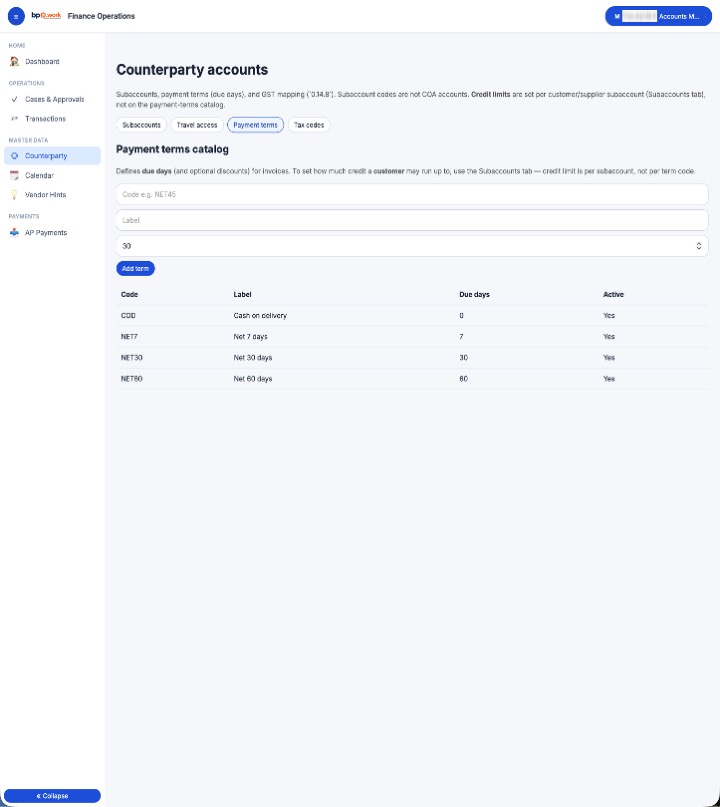
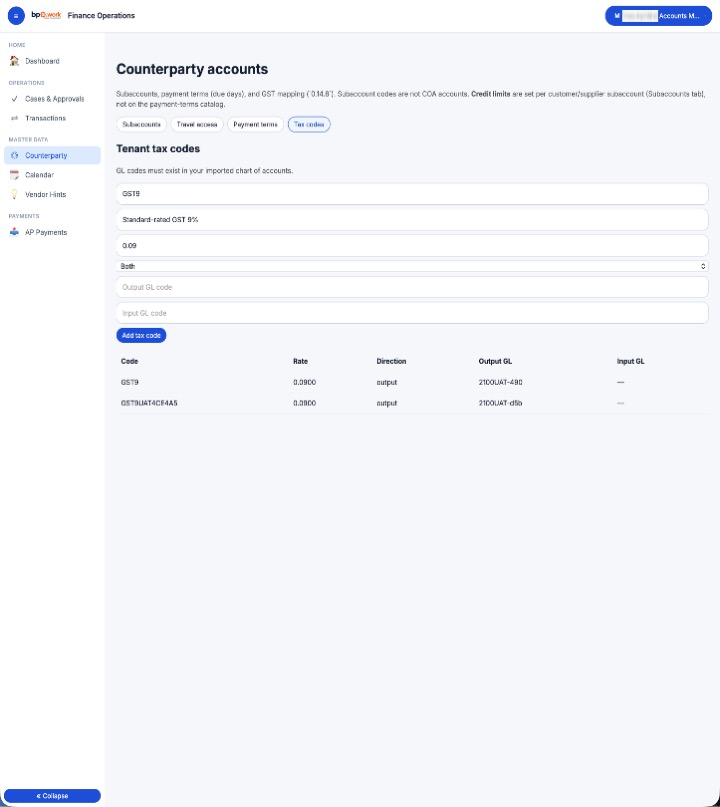
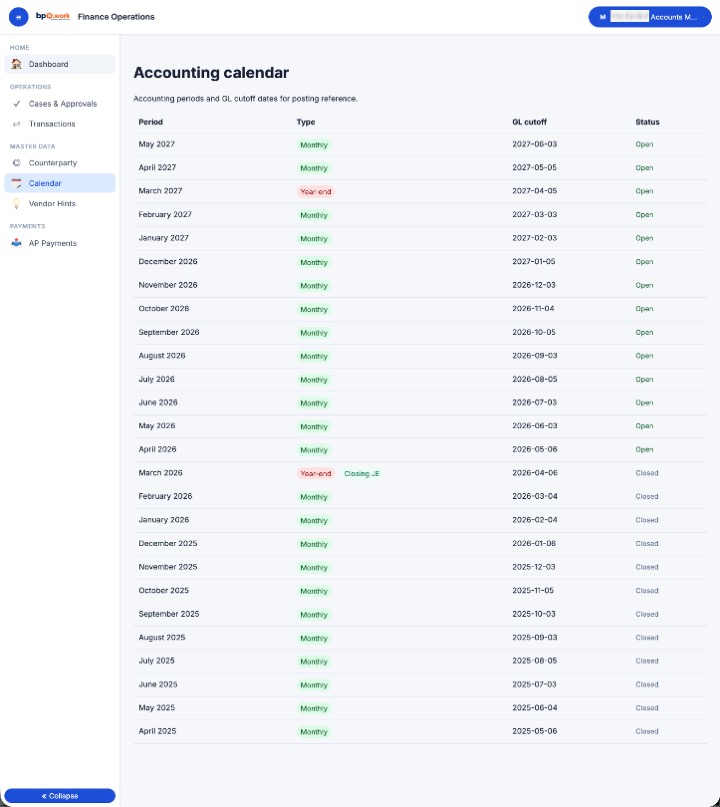
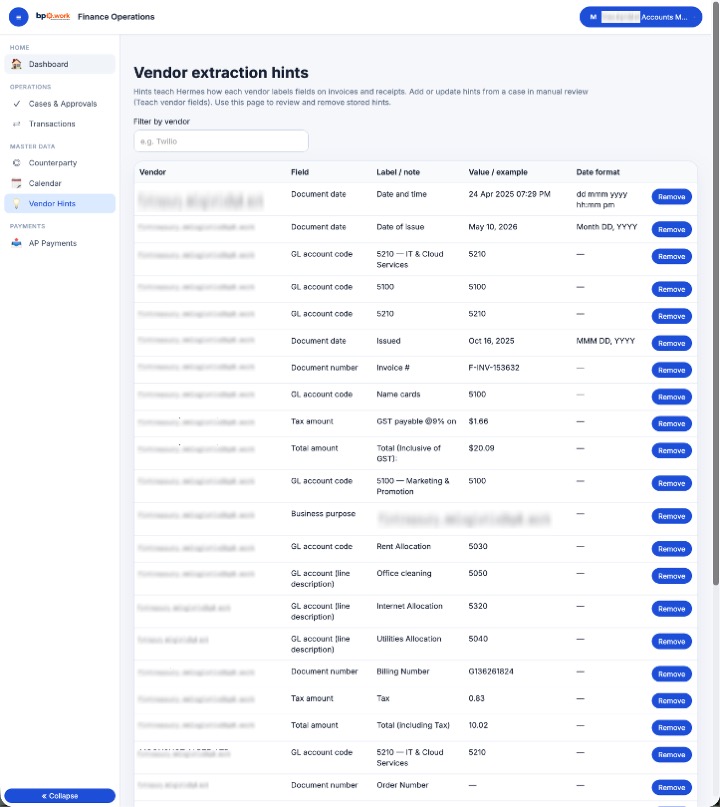
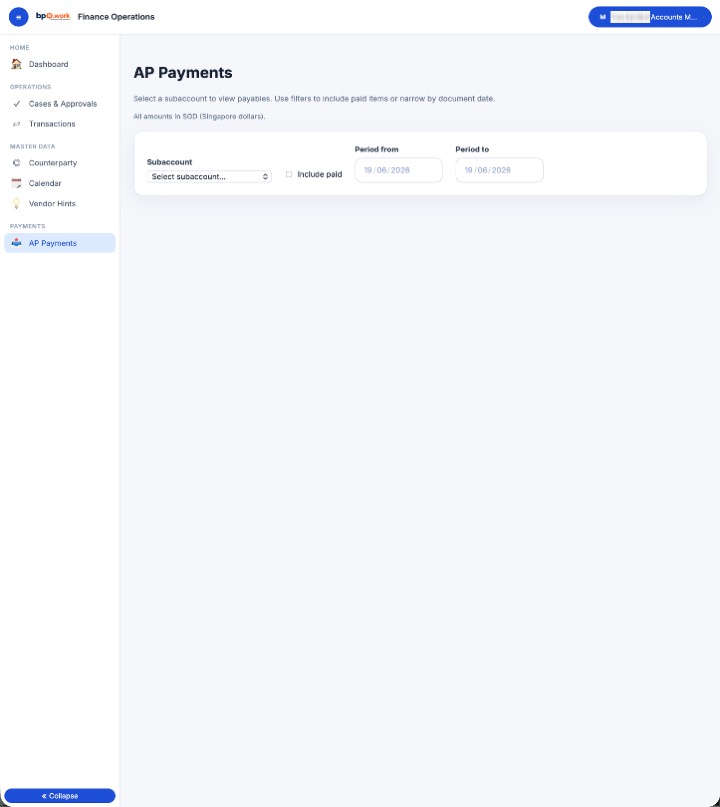
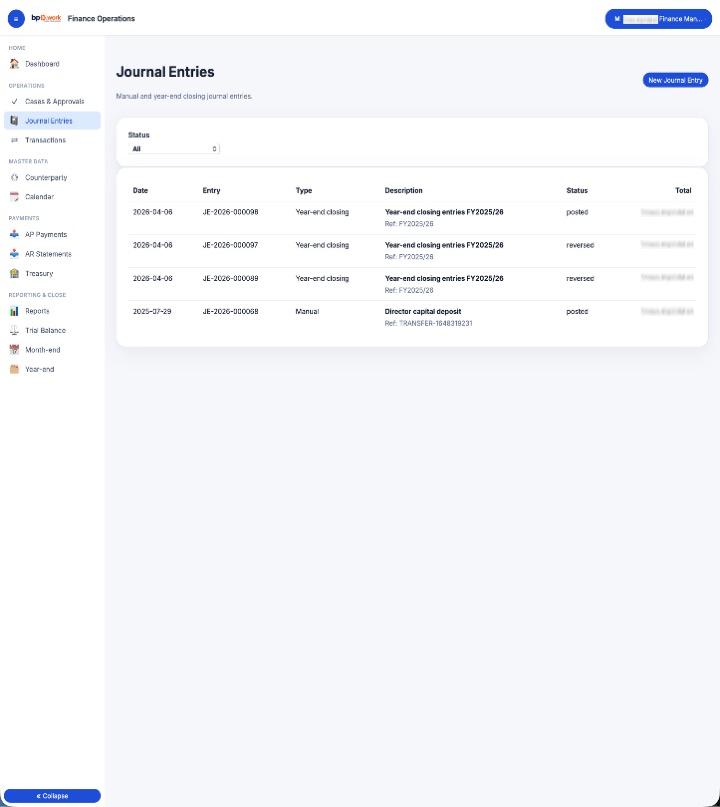
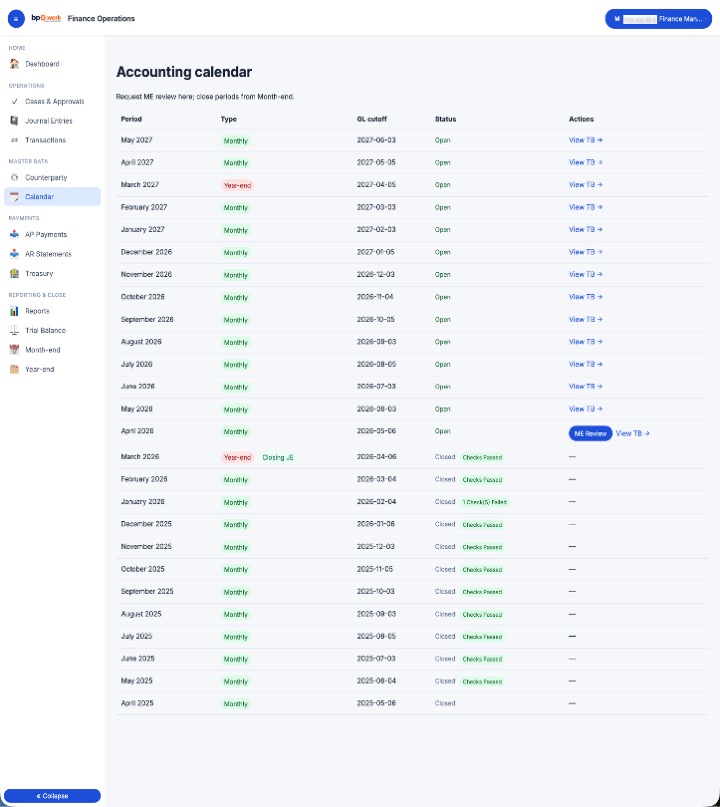
So I started building an agentic accounting department.
What began as a practical solution to a small business problem gradually evolved into something much larger.
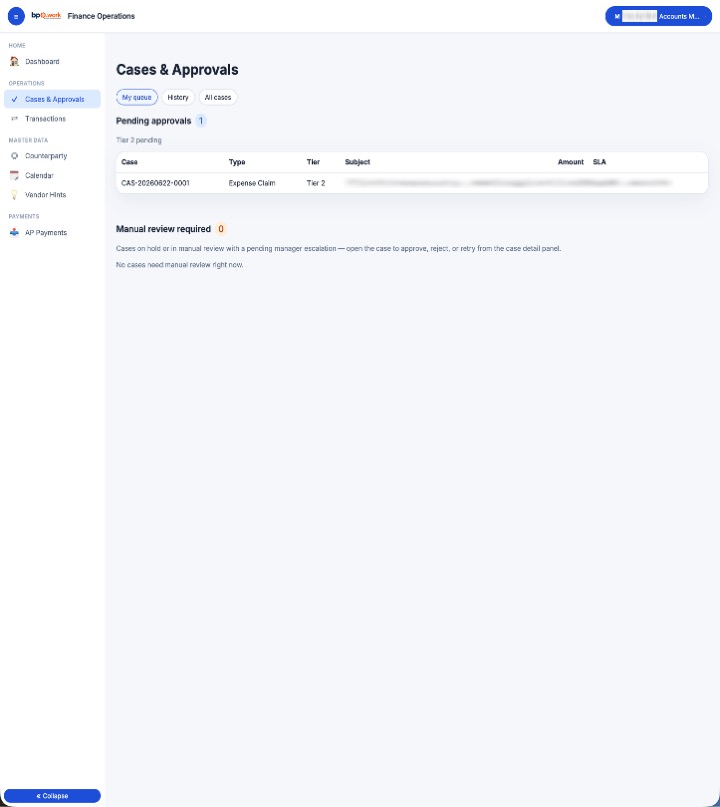
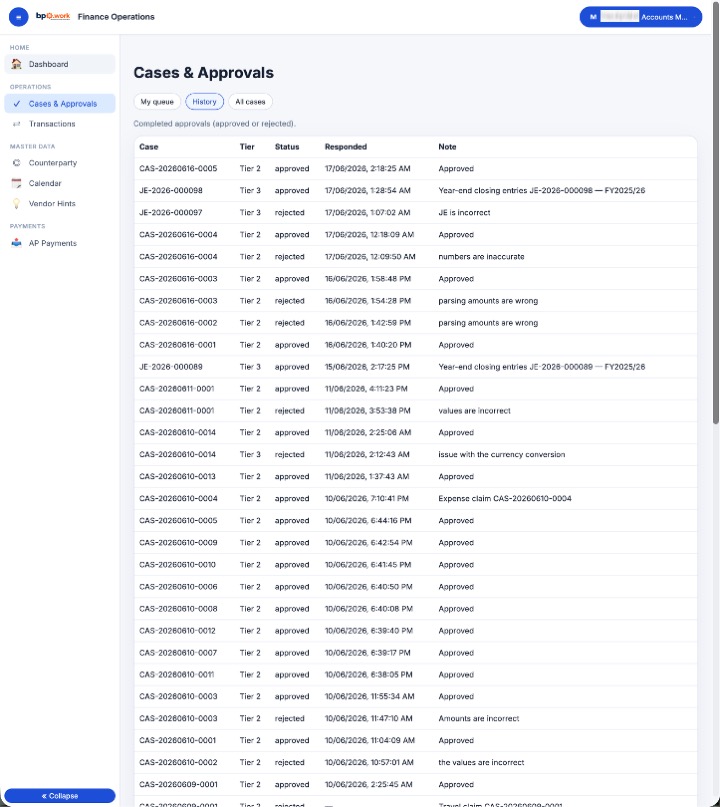
A properly run Accounts and Finance Department is built around controls, segregation of duties, approval authorities, audit trails, policies, and governance.
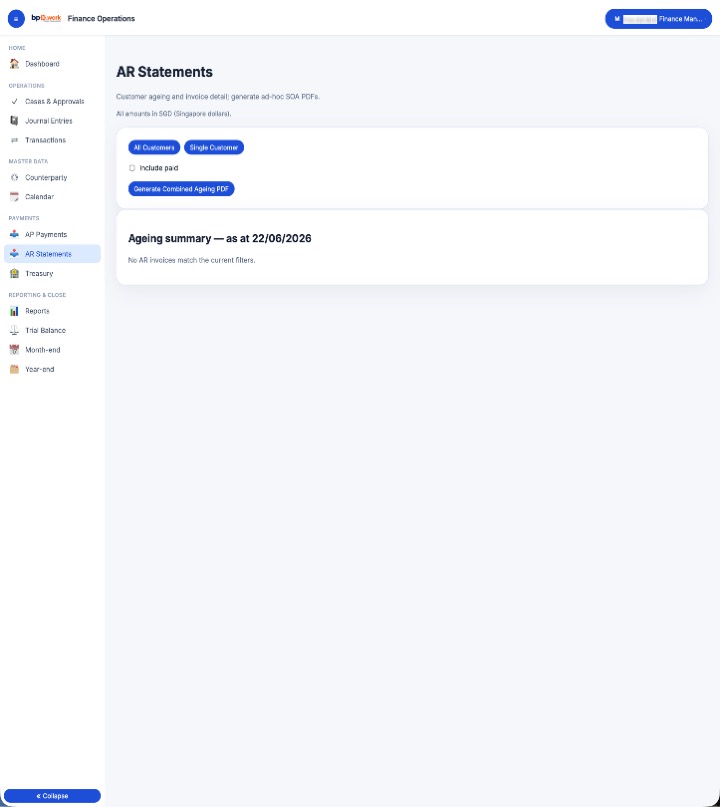
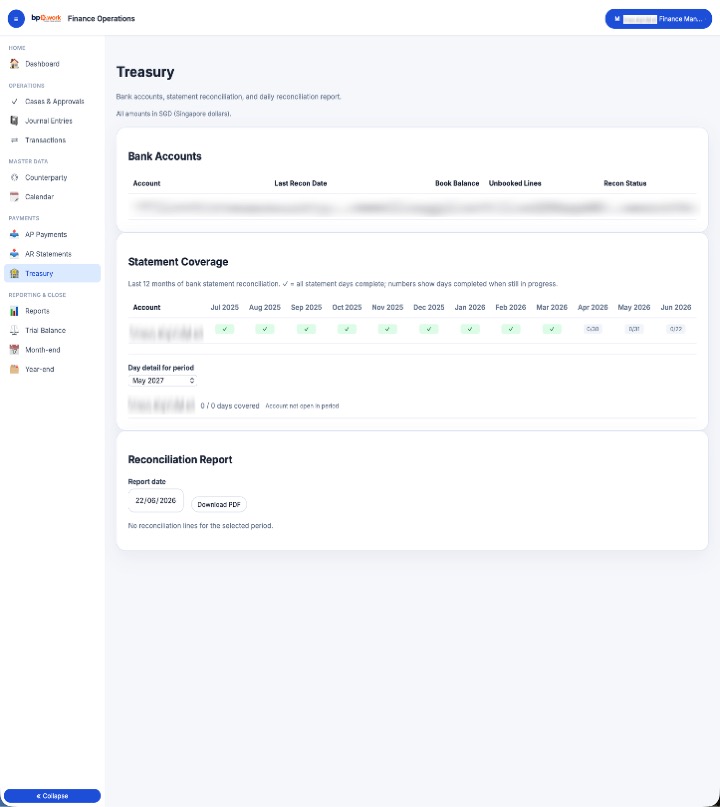
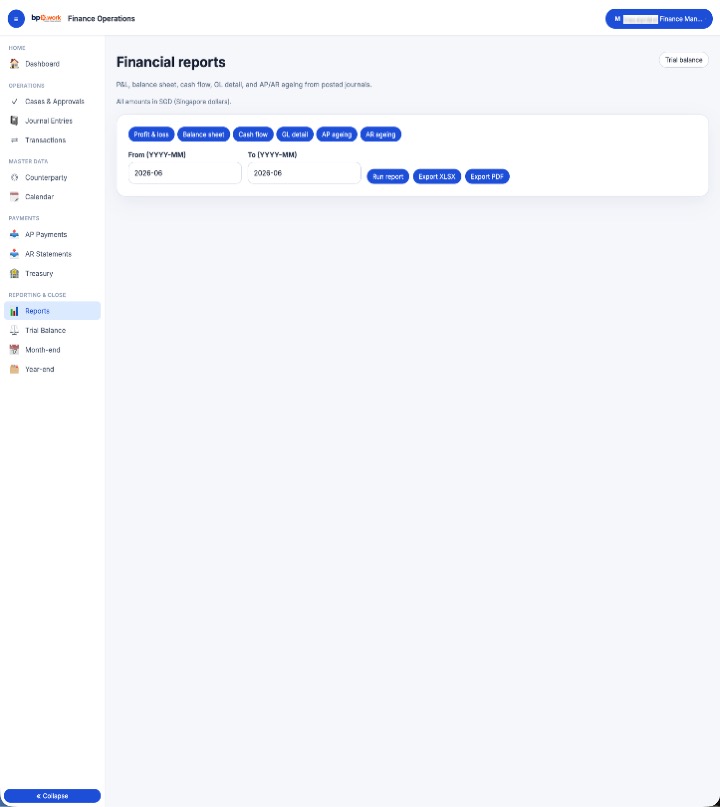
Rather than building a collection of AI tools, I designed the platform the same way I would structure an actual Accounts and Finance Department.
Each function has a specific role.
Each role has defined responsibilities.
Each transaction follows a documented workflow.
Each approval follows delegated authority limits.
Each exception is escalated to the appropriate human decision maker.
Routine work is handled automatically.
Judgement, accountability and governance remain with people.
The objective was never to replace finance professionals.
The objective was to replicate the structure, discipline and controls of a finance department while eliminating as much routine administrative work as possible.
The result is an agentic accounting department that continues to evolve as both a practical business tool and an experiment in how far exception-based finance operations can be taken.
Download the bp0.work finance platform profile here.
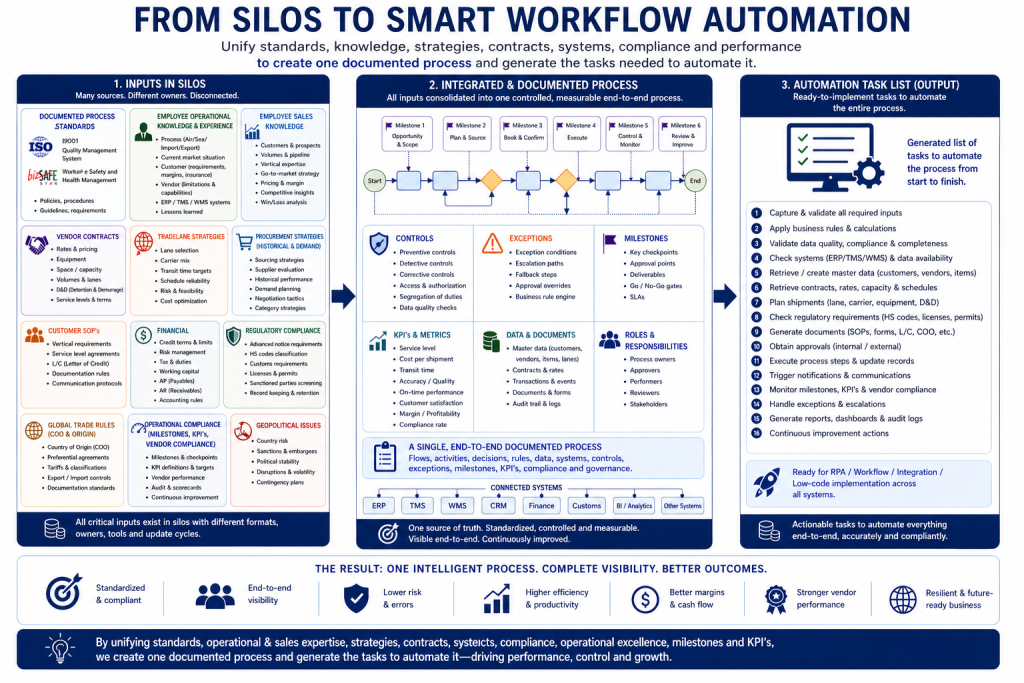
There’s a growing frustration around how slowly the freight forwarding and logistics industry is adopting automation. Many IT vendors have entered the space with strong expectations, only to step back after struggling to gain traction. From the outside, it often looks like resistance to change. From the inside, the reality is more complicated.
At first glance, freight forwarding appears highly repetitive. Emails, documents, shipment updates, billing. It feels like an ideal candidate for automation. But once you look closer, the process is not just a sequence of tasks. It’s a web of decisions, exceptions, and dependencies.
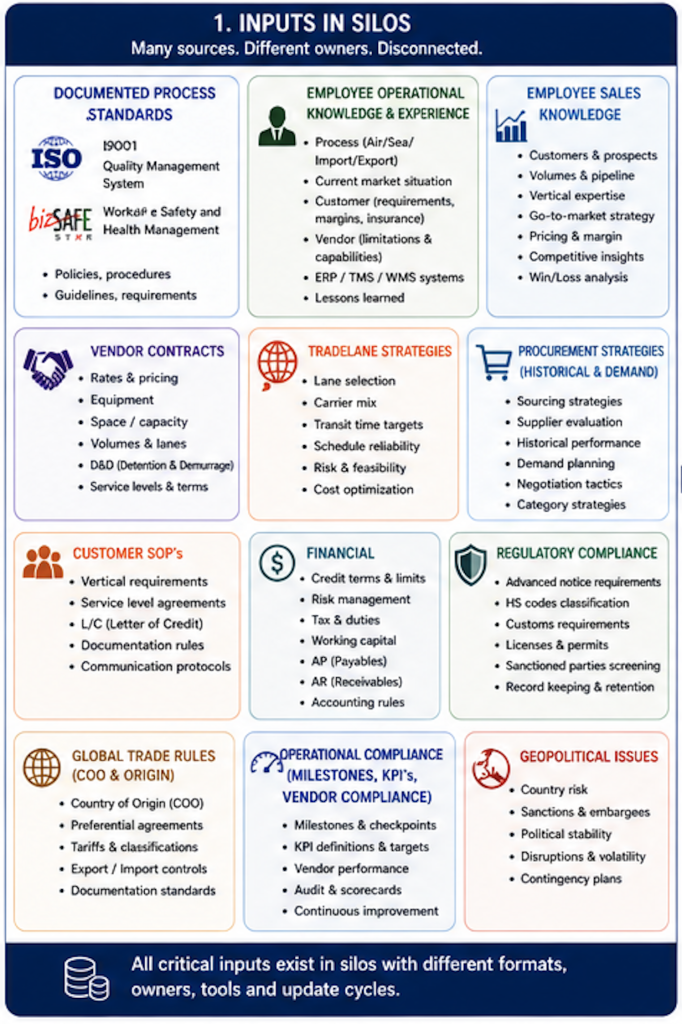
A single shipment can involve:
Customer-specific SOPs and service expectations
Vendor constraints on space, equipment, and routing
Rapidly changing market conditions
Financial considerations such as margins, credit limits, and working capital
Regulatory requirements including customs, licenses, and trade compliance
System limitations across ERP, TMS, and WMS platforms
Geopolitical disruptions affecting routes and costs
None of this sits in one place.
The real challenge is not technology. It’s fragmentation.
Knowledge is spread across:
Operations teams who understand how shipments actually move
Sales teams who know the customer, volumes, and pricing strategy
Procurement teams managing carriers and contracts
Finance teams controlling risk and revenue recognition
Compliance teams managing regulatory exposure
Each group holds a piece of the process. Very little of it is fully documented end-to-end.
This creates two core problems.
First, processes are often incomplete. What exists in SOPs typically covers the “standard case,” but not the real-world exceptions that happen daily. Automation struggles in environments where exceptions are not clearly defined.
Second, decision-making is embedded in people, not systems. Experienced operators constantly make judgment calls based on context. Vendor reliability, customer sensitivity, margin pressure, or shipment urgency. These decisions are rarely written down, but they are critical to execution.
When IT vendors try to automate such environments, they face a moving target. What looks like a simple workflow quickly expands into a complex set of rules, exceptions, and dependencies. Implementation timelines stretch. Scope increases. Confidence drops. Eventually, projects stall or are abandoned.
This is why many automation initiatives in freight forwarding fail before they even begin. Not because the technology doesn’t work, but because the process is not ready.
There is a way forward, but it requires a shift in approach.
Automation should not start with tools. It should start with clarity.
Companies need to:
Document processes beyond the standard flow, including exceptions and controls
Consolidate knowledge from operations, sales, procurement, finance, and compliance
Define decision logic where possible, and clearly separate what remains judgment-based
Align data structures across systems
Establish milestones, KPIs, and ownership
Only then does automation become practical.
When this foundation is in place, something changes. The process becomes visible. Dependencies are understood. Tasks can be broken down. At that point, automation is no longer an abstract concept. It becomes a series of clearly defined steps that can be implemented.
The industry is not slow because it resists automation. It’s slow because the underlying processes are complex, fragmented, and often undocumented.
Once that is addressed, automation doesn’t just become possible. It becomes inevitable.