Part 1: From Zero to Good: Building a Freight Forwarding Company
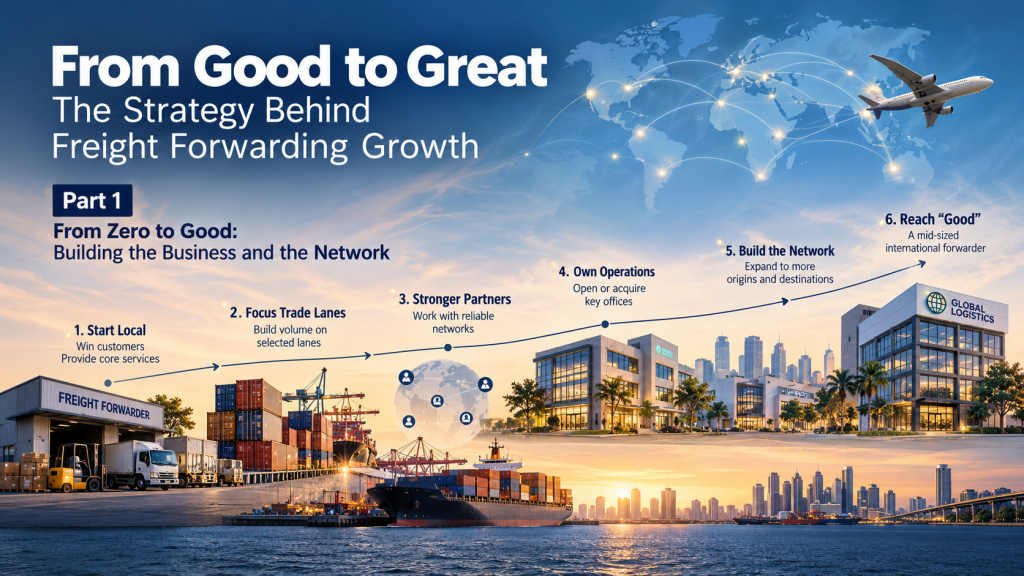
A proven model of building a freight forwarding company:
Start locally. Win customers. Develop relationships with overseas forwarders. Concentrate on trade lanes where the business grows. Replace partners with your own operations when sufficient volume justifies the investment. Then repeat the process.
Over time, a small local forwarder can become a substantial international company.
Two characteristics make this model particularly interesting.
The first is that freight forwarding can be operated as an asset-light business. The company makes little to no investment in capital-intensive logistics assets such as warehouses, CFS facilities, large truck fleets or other physical logistics infrastructure. It may own selected assets, such as office premises, individual trucks or equipment, where there is a practical or economic reason to do so, but physical asset ownership is not central to the business model.
The second is the way growth can be financed.
Instead of relying heavily on debt or external investors, expansion can be financed primarily from the profits generated by the existing business.
Together, these principles create a disciplined growth model:
Build the business first. Let the business justify the investment. Use the investment to strengthen the network. Then allow the stronger network to create more business.
This is the journey from zero to good.
Stage 1: Start as a Local Forwarder
The company begins with the fundamental forwarding services:
Pickup/delivery + handling + customs clearance + air/ocean freight
It can control the local side of the shipment but cannot independently provide the same service overseas.
So it joins or develops relationships with a network of other independent forwarders that provide equivalent capabilities at origin and destination.
That creates the first viable international product:
Local capability + overseas partner = door-to-door forwarding
Very little fixed network investment is required.
The company does not need its own operation in Germany to offer a Singapore-Germany service. A German forwarding partner can provide the pickup, customs clearance, handling or delivery required at the other end.
The same model can be repeated across multiple countries.
The company’s primary assets at this stage are therefore not warehouses or CFS facilities. They are its people, customer relationships, forwarding expertise, carrier relationships and overseas partner network.
Capital requirements remain relatively modest, allowing management to concentrate its available resources on generating and managing business.
Stage 2: Develop Focused Trade Lanes
As the company grows, certain trade lanes naturally become more important.
Perhaps Singapore-Germany becomes significant, or China-Singapore, or Singapore-US.
This matters because volume becomes concentrated rather than simply increasing in aggregate.
The company develops deeper relationships with selected overseas partners on those lanes. Business begins flowing in both directions:
Locally controlled business → overseas partner
and
Partner-controlled/routed business → local company
This creates a reinforcing cycle:
More local business → stronger overseas relationship → more routed business → more volume → greater relevance to the partner → more routed business
The relationship becomes increasingly valuable to both companies.
This is an important stage in the development of the forwarder because it begins creating trade-lane density.
Instead of trying to become equally strong everywhere, the company develops greater strength on selected origin-destination combinations where its customer base and partner relationships are producing meaningful volume.
At this stage, partner selection becomes strategically important.
Stage 3: Move Toward Stronger Network Partners
As the business becomes larger, the limitations of a loose collection of small independent agents eventually become visible.
Service levels vary. Systems differ. Communication standards differ. Financial strength differs. Management priorities differ.
And when something goes wrong, accountability can become difficult.
This creates a problem for the growing forwarder.
The customer does not particularly care that several independent companies are involved in moving the shipment.
The customer bought a door-to-door service.
One solution is therefore to develop a closer relationship with a larger independent or medium-sized forwarding network.
This may reduce some flexibility in choosing individual agents, but it can improve:
coverage, consistency, reliability, systems, buying power and accountability.
The company is beginning to sell more than transportation between two points.
It is developing a more dependable network product.
Importantly, this remains a capital-efficient way of improving international capability.
Rather than opening dozens of overseas offices, the company uses stronger partnerships to extend its reach while concentrating its own resources on the markets where it already has meaningful business.
Stage 4: Replace Partners With Owned Operations
Eventually, a particular trade lane becomes sufficiently important that using an agent is no longer the optimal solution.
This creates the first major critical-mass decision.
The question becomes:
At what level of existing and expected business does owning the overseas operation produce better economics, control and service than continuing to use an agent?
The company may establish its own office or acquire an existing local forwarder. That changes both the economics and the product. The company gains control over both ends of the shipment.
It can retain more of the forwarding margin, improve accountability, introduce common processes and service standards, and gain direct access to customers in the overseas market.
But something even more important happens.
The new office does not only service the shipments that justified opening it.
It starts generating business itself.
Salespeople in the new country win local customers. Those customers generate exports and imports. Some of that freight moves to existing offices elsewhere in the network.
The growth cycle therefore expands:
Existing volume → own office → improved service and control → local sales → new customers → additional bilateral volume → stronger trade lane
The investment begins reinforcing the business that originally justified it.
Stage 5: Build an Owned Network
The same logic can now be repeated. A second market reaches critical mass. Then another. Some locations are opened organically. Others may be acquired because acquisition provides an established customer base, experienced employees, licenses, relationships and revenue from the first day.
Gradually, the structure changes:
Agent network → hybrid network → predominantly owned network
The company is no longer simply a local forwarder with overseas agents.
It has become a multinational forwarding company.
And every additional location potentially increases the value of the existing network.
A new office does not simply create one additional market. It creates new commercial relationships with multiple existing locations.
An office in Singapore can generate business with Germany. Germany can generate business with China. China can generate business with the United States. The United States can generate business with Singapore. The number of potential trade relationships grows as the network expands.
This is where the network itself starts becoming an increasingly important competitive capability.
Stage 6: Reach “Good”
Continue this process for 10, 20 or 30 years and the result can be a substantial mid-sized international freight forwarder.
Yet the organizational structure can remain surprisingly close to the model from which the company developed.
Most employees still contribute directly to generating, executing or managing business:
Sales → customer service → operations → customs → finance → local management
Corporate functions remain relatively lean.
There may be regional management, procurement, IT, finance, HR and product functions, but the company has not developed the extensive central structures associated with the largest global forwarding organizations.
The physical asset base can also remain relatively small compared with the revenue generated.
Warehouses, CFS facilities, large truck fleets and other capital-intensive infrastructure are generally provided by external specialists unless there is a specific strategic or economic reason for ownership.
Capital is instead concentrated primarily on people, offices, systems and network development.
The result can be an economically efficient forwarding organization with relatively low fixed-asset requirements.
It has become good at freight forwarding. It has experienced people. It has customers. It has reliable basic air and ocean freight capabilities. It has an international network. It has increasing purchasing power. And it has a business model capable of generating sustainable profits.
The Zero-to-Good Flywheel
The entire development model can be summarized as a freight-forwarding flywheel:
Win local customers
→ Generate export/import volume
→ Strengthen selected trade lanes
→ Develop stronger overseas partnerships
→ Receive routed business
→ Increase trade-lane density
→ Reach critical mass
→ Open or acquire an own office
→ Improve service, control and margin retention
→ Generate local business in the new market
→ Increase network volume and profitability
→ Reinvest profits into the next market
↺
Each turn of the flywheel strengthens the organization.
More customers create more freight.
More freight creates greater trade-lane density.
Greater density justifies greater network control.
Greater network control improves the product and creates new commercial opportunities.
Those opportunities generate additional profits that can finance the next stage.
There is therefore an important principle underlying the entire Zero-to-Good model:
Build the network behind the freight.
The company does not first construct an expensive international network and then hope enough freight arrives to support it.
The freight comes first.
The network follows.
Financing Growth From the Business
The financing model is an essential part of this strategy.
The company can choose to finance expansion primarily through profits generated by the existing business.
The logic is straightforward:
Business → profit → investment → additional capability → more business → more profit
The asset-light operating model makes this possible.
Because relatively little capital needs to be committed to warehouses, CFS facilities and other physical logistics assets, a greater proportion of available investment can be directed toward commercial and network development.
Profits can finance a new office. They can finance additional salespeople. They can finance systems. They can finance regional functions. They can contribute toward acquisitions.
And as those investments generate additional business and profit, further investments become possible.
But there is an unavoidable consequence.
The speed and size of investment are constrained by the profits the company generates.
A company cannot continuously invest substantially more than it earns without obtaining capital from somewhere else.
That means investments tend to happen progressively.
One market is developed. Then another. One capability is added. Then another.
The company grows within the financial capacity created by the existing organization.
A Constraint That Creates Discipline
At first glance, limiting investment to internally generated funds may appear to be a disadvantage.
And in one sense it is.
A company with access to substantial external capital could potentially expand faster.
It could acquire several companies simultaneously, enter multiple countries, build infrastructure or invest heavily in technology and organizational capabilities ahead of existing demand.
A self-financed company has fewer options.
But that constraint also creates discipline.
Every significant investment has to answer a fundamental question:
Does the existing or realistically accessible business justify this investment?
A new office cannot simply be opened because a market looks attractive on a strategy presentation.
A meaningful commercial case has to exist.
Expansion therefore tends to follow proven business rather than anticipated business.
This reduces the risk of building an expensive network that customers never fill.
Independence Has Value
There is another side to the financing model.
By relying primarily on internally generated profits, the company can preserve a high degree of financial and strategic independence.
It is less dependent on external investors seeking returns within a particular investment horizon.
It is less dependent on lenders imposing financial conditions on the business.
Ownership and management can therefore take a longer-term view.
A trade lane can be developed patiently. A market can take several years to mature. Customer relationships can be built over decades. Profits can be reinvested rather than maximized for short-term distribution.
The trade-off is therefore not simply:
More capital versus less capital.
It is:
Faster access to investment capital versus greater financial independence and control over the company’s long-term direction.
For a company moving from zero to good, that trade-off can work remarkably well.
From Zero to Good
None of this requires an especially complicated strategy.
In fact, its strength comes partly from its simplicity.
Win customers.
Execute their freight well.
Concentrate on trade lanes where you develop strength.
Build strong overseas partnerships.
Replace partners with owned operations when the business justifies it.
Remain asset-light where ownership does not create sufficient value.
Generate profits.
Reinvest those profits into the next stage of the network.
Then repeat.
Over many years, this can transform a small local forwarder into a substantial multinational forwarding company.
The company has built its network largely behind the freight, allowing proven business to determine where scarce investment capital should go.
The same discipline that limits the speed of expansion also protects the company from overextending itself and allows it to remain independent.
For the journey from zero to good, this can be an exceptionally effective model.
But success eventually creates a new problem.
The company reaches a size where simply repeating what worked before may no longer be enough.
Some of the capabilities required to attract larger customers, increase network density and compete at the next level may need to be built before the freight exists to justify them.
The investments may also become larger than those required during the company’s earlier development.
And suddenly the principles that helped build a successful, independent forwarder create a new strategic question:
How do you go from good to great when the next stage of growth requires investing ahead of the business rather than behind it?
That is the subject of Part 2.
Leave a Reply
You must be logged in to post a comment.